Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
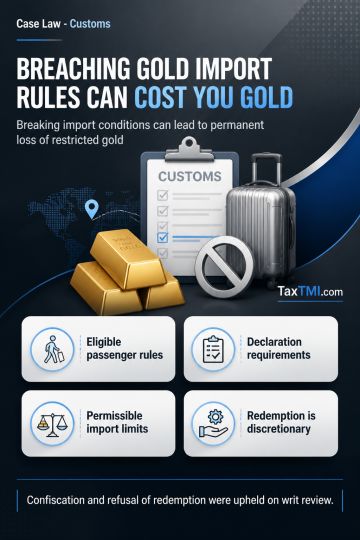
Restricted gold import conditions: breach permits absolute confiscation, while redemption remains discretionary and is rarely disturbed on writ review...
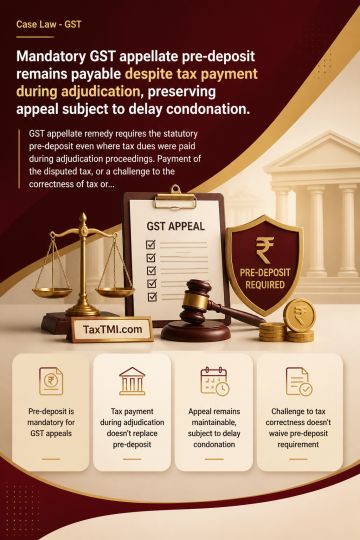
GST appellate remedy requires the statutory pre-deposit even where tax dues were paid during adjudication proceedings. Payment of the disputed tax, or a challenge to the correctness of tax or penalty, does not dispense with this filing condition; those issues must be determined on the appeal's merits. The petitioner could pursue the statutory appeal only after making the prescribed deposit and filing a delay-condonation application. The appellate authority was directed to consider the delay application sympathetically and, if satisfied, decide the appeal on merits.
GST appellate remedy requires the statutory pre-deposit even where tax dues were paid during adjudication proceedings. Payment of the disputed tax, or a challenge to the correctness of tax or penalty, does not dispense with this filing condition; those issues must be determined on the appeal's merits. The petitioner could pursue the statutory appeal only after making the prescribed deposit and filing a delay-condonation application. The appellate authority was directed to consider the delay application sympathetically and, if satisfied, decide the appeal on merits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921