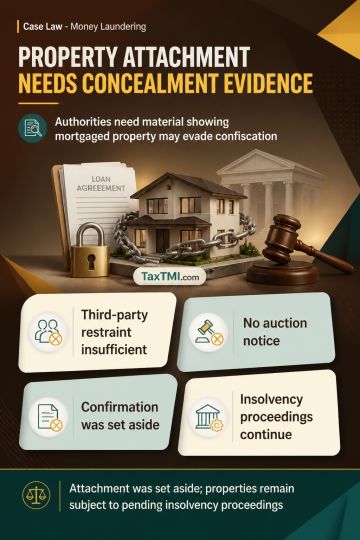
Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Customs assessment information portal centralises rulings and guidance to promote consistent classification, valuation, transparency and informed comp...
Composite show-cause notices spanning multiple financial years are jurisdictionally invalid, allowing writ review despite an alternative appellate rem...
Section 80C deduction omitted from an original return cannot be introduced through rectification of an intimation under section 143(1), because no such claim was made during return processing. Where evidence of an eligible fixed-deposit investment is available, the taxpayer may instead seek condonation to file a revised return and make the deduction claim in that return in accordance with law. The rectification claim remains unavailable, while the revised-return route is preserved subject to condonation.
Section 80C deduction omitted from an original return cannot be introduced through rectification of an intimation under section 143(1), because no such claim was made during return processing. Where evidence of an eligible fixed-deposit investment is available, the taxpayer may instead seek condonation to file a revised return and make the deduction claim in that return in accordance with law. The rectification claim remains unavailable, while the revised-return route is preserved subject to condonation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916