Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
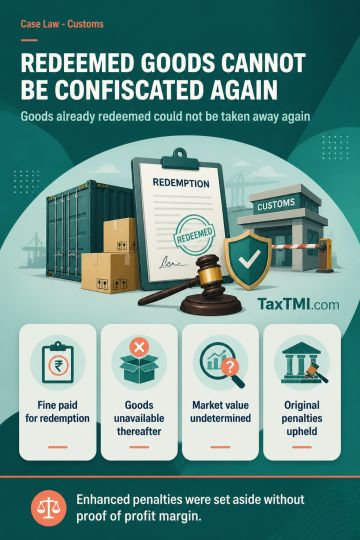
Absolute confiscation of imported computer hard discs was set aside because the goods had already been redeemed on payment of fine and were unavailable for further redemption; the confiscation merits had attained finality. Reliance on Supreme Court precedent supporting redemption meant that a subsequent absolute-confiscation direction was non-est in law. Enhanced penalties on the importer and its business head were also set aside because the original penalties were proportionate to the offence and market value had not been determined to establish the profit margin. The adjudication order allowing redemption and imposing the original penalties was sustained.
Absolute confiscation of imported computer hard discs was set aside because the goods had already been redeemed on payment of fine and were unavailable for further redemption; the confiscation merits had attained finality. Reliance on Supreme Court precedent supporting redemption meant that a subsequent absolute-confiscation direction was non-est in law. Enhanced penalties on the importer and its business head were also set aside because the original penalties were proportionate to the offence and market value had not been determined to establish the profit margin. The adjudication order allowing redemption and imposing the original penalties was sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918