Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
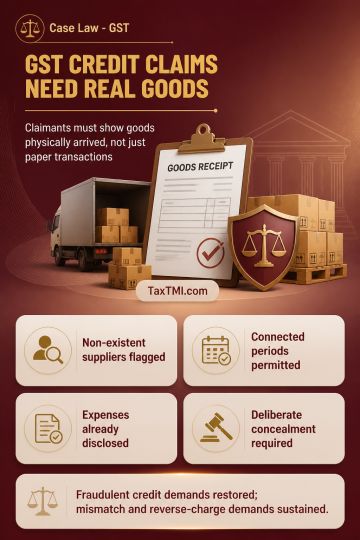
Input tax credit claimed on invoices issued by non-existent suppliers may attract Section 74 where the notice sets out foundational facts indicating fraud, wilful misstatement or suppression. The claimant must establish actual receipt and physical movement of goods; invoices and banking records alone do not prove transaction genuineness. A consolidated notice may cover multiple financial years because the statutory wording permits proceedings for connected periods. Conversely, reverse charge liability cannot be pursued under Section 74 merely from omissions when relevant expenses were disclosed in accounts and financial statements; deliberate non-disclosure is required. Input tax credit mismatch and reverse charge demands were sustained under Section 73 with consequential interest and penalty, while fraudulent credit demands were restored under Section 74.
Input tax credit claimed on invoices issued by non-existent suppliers may attract Section 74 where the notice sets out foundational facts indicating fraud, wilful misstatement or suppression. The claimant must establish actual receipt and physical movement of goods; invoices and banking records alone do not prove transaction genuineness. A consolidated notice may cover multiple financial years because the statutory wording permits proceedings for connected periods. Conversely, reverse charge liability cannot be pursued under Section 74 merely from omissions when relevant expenses were disclosed in accounts and financial statements; deliberate non-disclosure is required. Input tax credit mismatch and reverse charge demands were sustained under Section 73 with consequential interest and penalty, while fraudulent credit demands were restored under Section 74.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918