Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
Contingency expenses, exempt-income disallowance, and royalty benchmarking: unsupported adjustments were deleted under consistent accounting and trans...
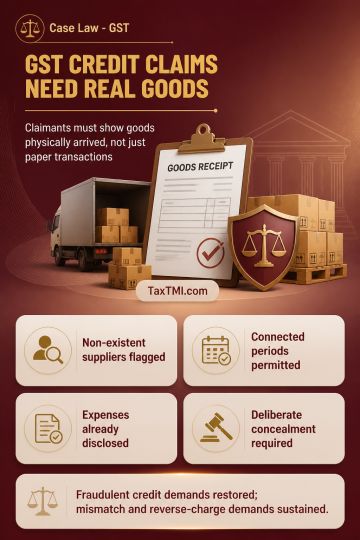
Input tax credit claimed on invoices issued by non-existent suppliers may attract Section 74 where the notice sets out foundational facts indicating fraud, wilful misstatement or suppression. The claimant must establish actual receipt and physical movement of goods; invoices and banking records alone do not prove transaction genuineness. A consolidated notice may cover multiple financial years because the statutory wording permits proceedings for connected periods. Conversely, reverse charge liability cannot be pursued under Section 74 merely from omissions when relevant expenses were disclosed in accounts and financial statements; deliberate non-disclosure is required. Input tax credit mismatch and reverse charge demands were sustained under Section 73 with consequential interest and penalty, while fraudulent credit demands were restored under Section 74.
Input tax credit claimed on invoices issued by non-existent suppliers may attract Section 74 where the notice sets out foundational facts indicating fraud, wilful misstatement or suppression. The claimant must establish actual receipt and physical movement of goods; invoices and banking records alone do not prove transaction genuineness. A consolidated notice may cover multiple financial years because the statutory wording permits proceedings for connected periods. Conversely, reverse charge liability cannot be pursued under Section 74 merely from omissions when relevant expenses were disclosed in accounts and financial statements; deliberate non-disclosure is required. Input tax credit mismatch and reverse charge demands were sustained under Section 73 with consequential interest and penalty, while fraudulent credit demands were restored under Section 74.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918