Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Page of 4921
Press 'Enter' after typing page number.
141 to 160 of 98411 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
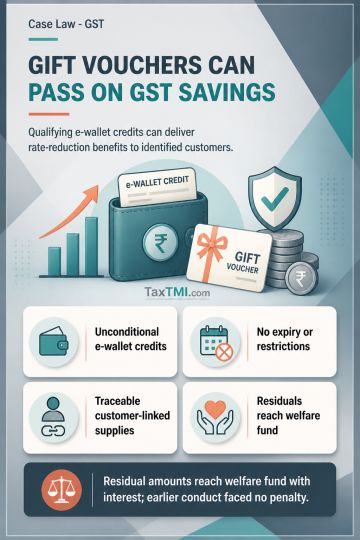
Section 171 permits GST rate-reduction benefits to be passed through electronic gift vouchers where e-wallet credits carry monetary value, are unconditional, have no expiry or usage restrictions, and are traceable to identified customers, invoices and supplies. System-generated labels such as "Offers and cashback" do not negate the documented link to the benefit. Benefits not traceable to identifiable recipients remain unpassed; after accounting for cancelled or returned supplies, the residual amount must be deposited in the Central Consumer Welfare Fund with applicable interest. The anti-profiteering penalty provision does not apply to conduct occurring before it came into force, so no penalty is leviable for that earlier period.
Section 171 permits GST rate-reduction benefits to be passed through electronic gift vouchers where e-wallet credits carry monetary value, are unconditional, have no expiry or usage restrictions, and are traceable to identified customers, invoices and supplies. System-generated labels such as "Offers and cashback" do not negate the documented link to the benefit. Benefits not traceable to identifiable recipients remain unpassed; after accounting for cancelled or returned supplies, the residual amount must be deposited in the Central Consumer Welfare Fund with applicable interest. The anti-profiteering penalty provision does not apply to conduct occurring before it came into force, so no penalty is leviable for that earlier period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921