Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
Contingency expenses, exempt-income disallowance, and royalty benchmarking: unsupported adjustments were deleted under consistent accounting and trans...
GST treatment of school-affiliation, annual registration and...
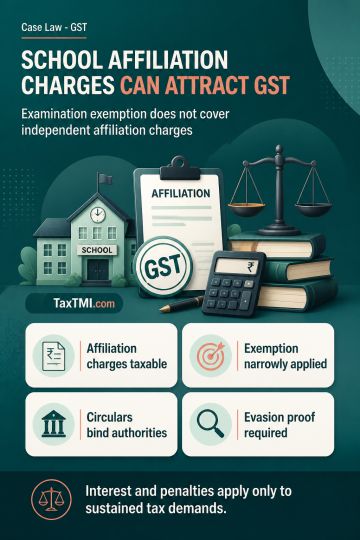
School-affiliation charges remain taxable where not directly connected with examinations, while extended limitation requires proof of deliberate tax evasion.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
GST treatment of school-affiliation, annual registration and late-registration charges turns on whether services directly relate to admission to or conduct of examinations. Affiliation and related administrative charges are treated as independent taxable supplies, with the examination-services exemption construed strictly; affiliation regularisation remains limited to its specified period. A consolidated show cause notice may cover multiple tax periods absent prejudice or jurisdictional defect. GST Council-based circulars on affiliation remain binding on departmental authorities. Amounts collected without separately charging GST require cum-tax valuation. Extended limitation requires affirmative proof of fraud, wilful misstatement or deliberate suppression with intent to evade tax; non-payment and delayed registration alone are insufficient. Interest and penalties survive only to the extent of sustained tax demands.
GST treatment of school-affiliation, annual registration and late-registration charges turns on whether services directly relate to admission to or conduct of examinations. Affiliation and related administrative charges are treated as independent taxable supplies, with the examination-services exemption construed strictly; affiliation regularisation remains limited to its specified period. A consolidated show cause notice may cover multiple tax periods absent prejudice or jurisdictional defect. GST Council-based circulars on affiliation remain binding on departmental authorities. Amounts collected without separately charging GST require cum-tax valuation. Extended limitation requires affirmative proof of fraud, wilful misstatement or deliberate suppression with intent to evade tax; non-payment and delayed registration alone are insufficient. Interest and penalties survive only to the extent of sustained tax demands.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918