Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Customs assessment information portal centralises rulings and guidance to promote consistent classification, valuation, transparency and informed comp...
Composite show-cause notices spanning multiple financial years are jurisdictionally invalid, allowing writ review despite an alternative appellate rem...
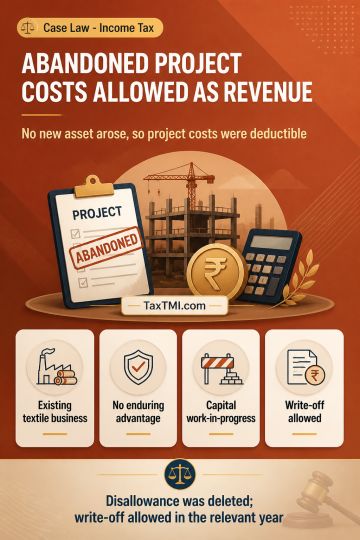
Expenditure on an abandoned towel-manufacturing expansion within an existing textile business was deductible as revenue expenditure because no completed capital asset or enduring advantage arose. Its initial classification as capital work-in-progress did not determine its character, which depended on its purpose and business context. The matching principle could not restrict a statutory deduction or compel spreading of expenditure; it applies only where the taxpayer elects to spread costs and the relevant conditions are met. The write-off was allowable in the relevant year, and the disallowance was deleted.
Expenditure on an abandoned towel-manufacturing expansion within an existing textile business was deductible as revenue expenditure because no completed capital asset or enduring advantage arose. Its initial classification as capital work-in-progress did not determine its character, which depended on its purpose and business context. The matching principle could not restrict a statutory deduction or compel spreading of expenditure; it applies only where the taxpayer elects to spread costs and the relevant conditions are met. The write-off was allowable in the relevant year, and the disallowance was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918