Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
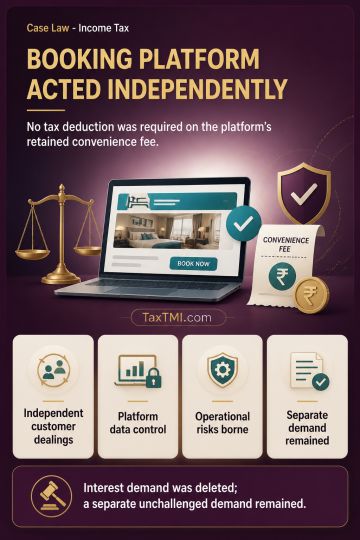
Section 194H applies only where the recipient earns commission or brokerage while acting in a representative capacity for the payer. An online ticketing platform that dealt independently with customers, controlled platform data, bore operational risks, remained liable for platform claims and remitted a fixed ticket amount irrespective of collections operated on a principal-to-principal basis. Its retained convenience fee for digital booking services was therefore not commission paid or constructively paid by the cinema operator, and no tax-deduction obligation arose. Interest for failure to deduct tax was consequential to the primary obligation and was deleted. A separate unchallenged demand remained unaffected.
Section 194H applies only where the recipient earns commission or brokerage while acting in a representative capacity for the payer. An online ticketing platform that dealt independently with customers, controlled platform data, bore operational risks, remained liable for platform claims and remitted a fixed ticket amount irrespective of collections operated on a principal-to-principal basis. Its retained convenience fee for digital booking services was therefore not commission paid or constructively paid by the cinema operator, and no tax-deduction obligation arose. Interest for failure to deduct tax was consequential to the primary obligation and was deleted. A separate unchallenged demand remained unaffected.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920