Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
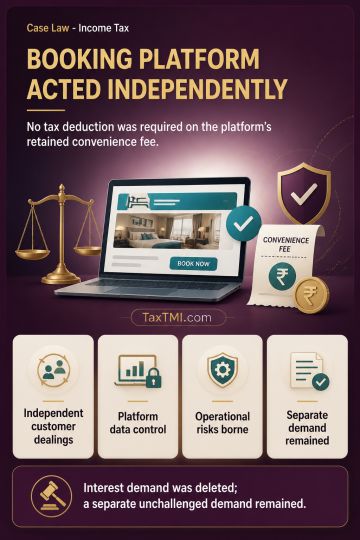
Section 194H applies only where the recipient earns commission or brokerage while acting in a representative capacity for the payer. An online ticketing platform that dealt independently with customers, controlled platform data, bore operational risks, remained liable for platform claims and remitted a fixed ticket amount irrespective of collections operated on a principal-to-principal basis. Its retained convenience fee for digital booking services was therefore not commission paid or constructively paid by the cinema operator, and no tax-deduction obligation arose. Interest for failure to deduct tax was consequential to the primary obligation and was deleted. A separate unchallenged demand remained unaffected.
Section 194H applies only where the recipient earns commission or brokerage while acting in a representative capacity for the payer. An online ticketing platform that dealt independently with customers, controlled platform data, bore operational risks, remained liable for platform claims and remitted a fixed ticket amount irrespective of collections operated on a principal-to-principal basis. Its retained convenience fee for digital booking services was therefore not commission paid or constructively paid by the cinema operator, and no tax-deduction obligation arose. Interest for failure to deduct tax was consequential to the primary obligation and was deleted. A separate unchallenged demand remained unaffected.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918