Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Page of 4921
Press 'Enter' after typing page number.
1721 to 1740 of 98411 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
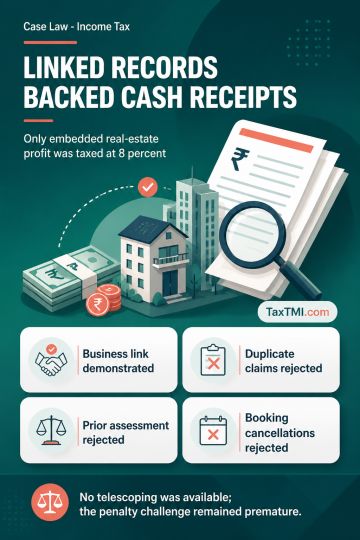
Third-party seized loose sheets can support an on-money addition only when corroborated or demonstrably connected to the assessee's business. Where flat-level particulars, cash receipts, the developer's role and offered profit established that connection, the Tribunal sustained the finding and quantification of on-money receipts, rejecting unsupported claims of duplicate entries, prior assessment and booking cancellations. As unaccounted real-estate receipts are business receipts, only their embedded profit is taxable; lacking a basis for a higher rate, the Tribunal reduced the estimated profit rate to 8 percent. No further telescoping was available because unaccounted expenditure had already been accepted as met from those receipts. Mere initiation of penalty proceedings was not appealable and the challenge was premature.
Third-party seized loose sheets can support an on-money addition only when corroborated or demonstrably connected to the assessee's business. Where flat-level particulars, cash receipts, the developer's role and offered profit established that connection, the Tribunal sustained the finding and quantification of on-money receipts, rejecting unsupported claims of duplicate entries, prior assessment and booking cancellations. As unaccounted real-estate receipts are business receipts, only their embedded profit is taxable; lacking a basis for a higher rate, the Tribunal reduced the estimated profit rate to 8 percent. No further telescoping was available because unaccounted expenditure had already been accepted as met from those receipts. Mere initiation of penalty proceedings was not appealable and the challenge was premature.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921