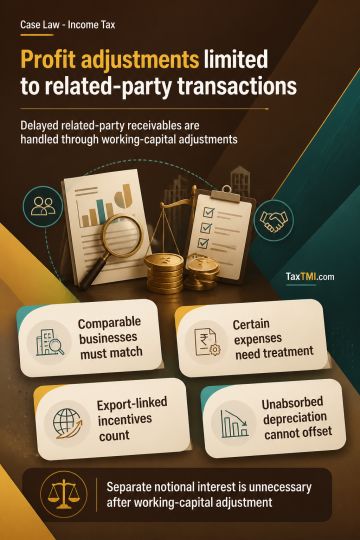
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Third-party seized loose sheets can support an on-money addition only when corroborated or demonstrably connected to the assessee's business. Where flat-level particulars, cash receipts, the developer's role and offered profit established that connection, the Tribunal sustained the finding and quantification of on-money receipts, rejecting unsupported claims of duplicate entries, prior assessment and booking cancellations. As unaccounted real-estate receipts are business receipts, only their embedded profit is taxable; lacking a basis for a higher rate, the Tribunal reduced the estimated profit rate to 8 percent. No further telescoping was available because unaccounted expenditure had already been accepted as met from those receipts. Mere initiation of penalty proceedings was not appealable and the challenge was premature.
Third-party seized loose sheets can support an on-money addition only when corroborated or demonstrably connected to the assessee's business. Where flat-level particulars, cash receipts, the developer's role and offered profit established that connection, the Tribunal sustained the finding and quantification of on-money receipts, rejecting unsupported claims of duplicate entries, prior assessment and booking cancellations. As unaccounted real-estate receipts are business receipts, only their embedded profit is taxable; lacking a basis for a higher rate, the Tribunal reduced the estimated profit rate to 8 percent. No further telescoping was available because unaccounted expenditure had already been accepted as met from those receipts. Mere initiation of penalty proceedings was not appealable and the challenge was premature.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921