Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
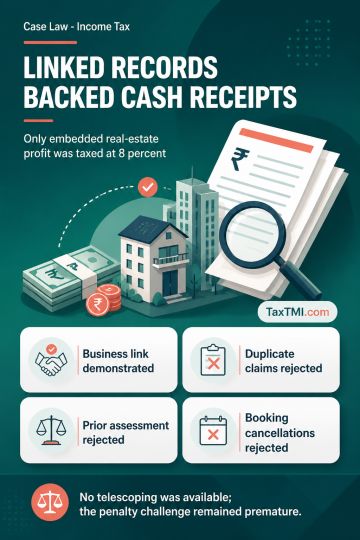
Third-party seized loose sheets can support an on-money addition only when corroborated or demonstrably connected to the assessee's business. Where flat-level particulars, cash receipts, the developer's role and offered profit established that connection, the Tribunal sustained the finding and quantification of on-money receipts, rejecting unsupported claims of duplicate entries, prior assessment and booking cancellations. As unaccounted real-estate receipts are business receipts, only their embedded profit is taxable; lacking a basis for a higher rate, the Tribunal reduced the estimated profit rate to 8 percent. No further telescoping was available because unaccounted expenditure had already been accepted as met from those receipts. Mere initiation of penalty proceedings was not appealable and the challenge was premature.
Third-party seized loose sheets can support an on-money addition only when corroborated or demonstrably connected to the assessee's business. Where flat-level particulars, cash receipts, the developer's role and offered profit established that connection, the Tribunal sustained the finding and quantification of on-money receipts, rejecting unsupported claims of duplicate entries, prior assessment and booking cancellations. As unaccounted real-estate receipts are business receipts, only their embedded profit is taxable; lacking a basis for a higher rate, the Tribunal reduced the estimated profit rate to 8 percent. No further telescoping was available because unaccounted expenditure had already been accepted as met from those receipts. Mere initiation of penalty proceedings was not appealable and the challenge was premature.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918