GST payment representations require record-based, reasoned decisions while substantive entitlement remains open for determination by competent authori...
Reassessment sanction under extended limitation required approval from the competent specified authority, invalidating proceedings approved by an inco...
Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment...
Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments...
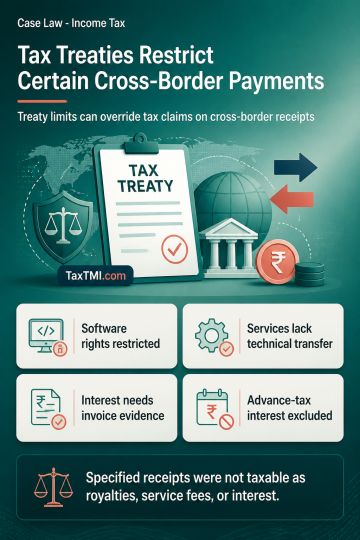
Treaty limitations on royalty taxation and the make-available condition restrict taxation of cross-border receipts despite transfer-pricing adjustments. Notional interest requires an invoice-wise factual basis and interest paid, credited, acknowledged as payable or made available; arm's-length recomputation cannot independently create interest taxable under the treaty. Standardised software supplied with restricted end-user rights, connectivity services without rights in equipment or processes, and lease rentals paid by a non-resident outside the treaty source rule do not constitute taxable royalty income. Testing, administrative reimbursements and non-technical managerial training are not fees for included services where they do not transmit independently usable technical capability. Non-residents are not liable for advance-tax interest for periods when deductible tax had to be excluded from advance-tax computation.
Treaty limitations on royalty taxation and the make-available condition restrict taxation of cross-border receipts despite transfer-pricing adjustments. Notional interest requires an invoice-wise factual basis and interest paid, credited, acknowledged as payable or made available; arm's-length recomputation cannot independently create interest taxable under the treaty. Standardised software supplied with restricted end-user rights, connectivity services without rights in equipment or processes, and lease rentals paid by a non-resident outside the treaty source rule do not constitute taxable royalty income. Testing, administrative reimbursements and non-technical managerial training are not fees for included services where they do not transmit independently usable technical capability. Non-residents are not liable for advance-tax interest for periods when deductible tax had to be excluded from advance-tax computation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920