Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
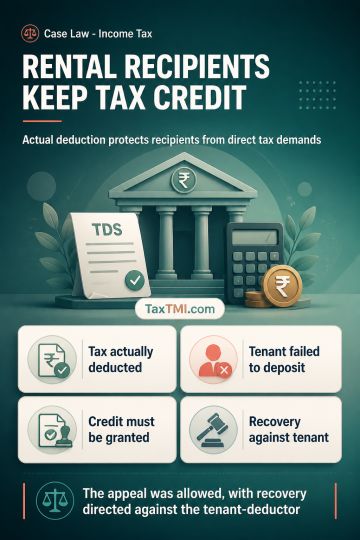
TDS credit for rental income remains available where the tenant has actually deducted tax but fails to deposit it with the Central Government. Actual deduction triggers statutory protection against a direct tax demand on the income recipient; the deductor's deposit default cannot undermine the recipient's income declaration or justify withholding credit. Recovery of the unpaid tax must be pursued against the tenant-deductor. Credit for tax deducted from rental income was therefore directed to be granted, and the appeal was allowed.
TDS credit for rental income remains available where the tenant has actually deducted tax but fails to deposit it with the Central Government. Actual deduction triggers statutory protection against a direct tax demand on the income recipient; the deductor's deposit default cannot undermine the recipient's income declaration or justify withholding credit. Recovery of the unpaid tax must be pursued against the tenant-deductor. Credit for tax deducted from rental income was therefore directed to be granted, and the appeal was allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918