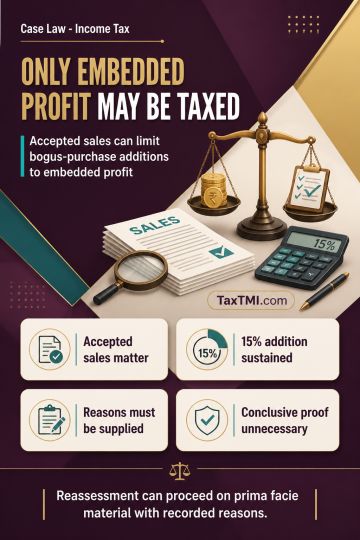
Bogus-purchase additions are limited to embedded profit where corresponding sales are accepted, while accommodation-entry information can support reas...
Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Statutory return of seized goods under Section 110(2) of the Customs Act arises where no notice is issued within the prescribed period or a validly extended period; continued retention is then impermissible. Compliance with Section 124 was disputed because the Department relied on contemporaneous proceedings as an oral show cause notice, while the affected parties challenged the documents' execution, explanation and voluntariness. Determining whether an oral notice satisfied statutory requirements required examination of statements and contemporaneous material, making writ jurisdiction unsuitable for resolving the factual dispute. Unconditional release was declined, with adjudication directed after a reasonable hearing.
Statutory return of seized goods under Section 110(2) of the Customs Act arises where no notice is issued within the prescribed period or a validly extended period; continued retention is then impermissible. Compliance with Section 124 was disputed because the Department relied on contemporaneous proceedings as an oral show cause notice, while the affected parties challenged the documents' execution, explanation and voluntariness. Determining whether an oral notice satisfied statutory requirements required examination of statements and contemporaneous material, making writ jurisdiction unsuitable for resolving the factual dispute. Unconditional release was declined, with adjudication directed after a reasonable hearing.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921