Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
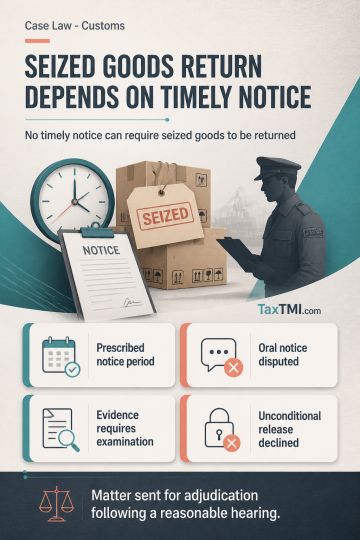
Statutory return of seized goods under Section 110(2) of the Customs Act arises where no notice is issued within the prescribed period or a validly extended period; continued retention is then impermissible. Compliance with Section 124 was disputed because the Department relied on contemporaneous proceedings as an oral show cause notice, while the affected parties challenged the documents' execution, explanation and voluntariness. Determining whether an oral notice satisfied statutory requirements required examination of statements and contemporaneous material, making writ jurisdiction unsuitable for resolving the factual dispute. Unconditional release was declined, with adjudication directed after a reasonable hearing.
Statutory return of seized goods under Section 110(2) of the Customs Act arises where no notice is issued within the prescribed period or a validly extended period; continued retention is then impermissible. Compliance with Section 124 was disputed because the Department relied on contemporaneous proceedings as an oral show cause notice, while the affected parties challenged the documents' execution, explanation and voluntariness. Determining whether an oral notice satisfied statutory requirements required examination of statements and contemporaneous material, making writ jurisdiction unsuitable for resolving the factual dispute. Unconditional release was declined, with adjudication directed after a reasonable hearing.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918