Human-probability test defeats political donation deductions where banking records mask accommodation-entry fund layering rather than genuine contribu...
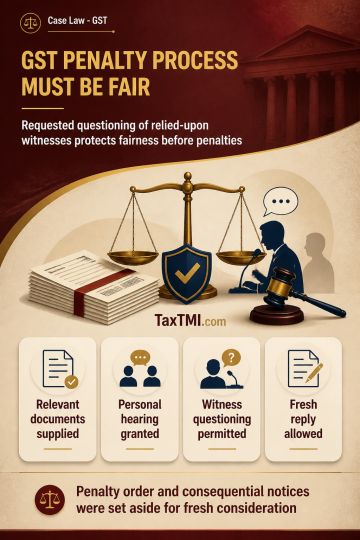
Cross-examination of persons whose statements are relied upon in GST penalty proceedings is necessary to satisfy principles of natural justice where the affected party specifically requests it. Denial of that opportunity before imposing penalty constitutes a serious procedural defect. The penalty order and consequential notices were set aside, with fresh consideration required after supplying relevant documents, granting a personal hearing, permitting cross-examination of relied-upon persons, and allowing a fresh reply. The merits of the underlying allegations remained open for independent reconsideration.
Cross-examination of persons whose statements are relied upon in GST penalty proceedings is necessary to satisfy principles of natural justice where the affected party specifically requests it. Denial of that opportunity before imposing penalty constitutes a serious procedural defect. The penalty order and consequential notices were set aside, with fresh consideration required after supplying relevant documents, granting a personal hearing, permitting cross-examination of relied-upon persons, and allowing a fresh reply. The merits of the underlying allegations remained open for independent reconsideration.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921