Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Page of 4921
Press 'Enter' after typing page number.
141 to 160 of 98411 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
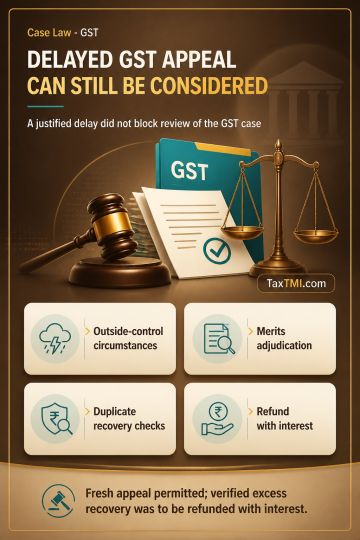
GST appellate limitation bound the Appellate Authority, but delay caused by circumstances beyond the taxpayer's control was treated as sufficient cause for condonation to prevent prejudice from denial of a merits hearing. A fresh statutory appeal could therefore be filed within the permitted period for adjudication on merits. Alleged duplicate recovery of GST demand required verification rather than an immediate factual finding; any excess recovery identified on verification was to be refunded with applicable interest.
GST appellate limitation bound the Appellate Authority, but delay caused by circumstances beyond the taxpayer's control was treated as sufficient cause for condonation to prevent prejudice from denial of a merits hearing. A fresh statutory appeal could therefore be filed within the permitted period for adjudication on merits. Alleged duplicate recovery of GST demand required verification rather than an immediate factual finding; any excess recovery identified on verification was to be refunded with applicable interest.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921