Tariff rate quota authorisations govern preferential imports of specified New Zealand goods through export certification and electronic customs debiti...
Electronic Continuity Bond Registration replaces manual container permissions, with quarterly reporting and re-export monitoring for duty-free contain...
Delayed transport documents failed to validate intercepted goods, sustaining transit-state penalties where the claimed interstate destination remained...
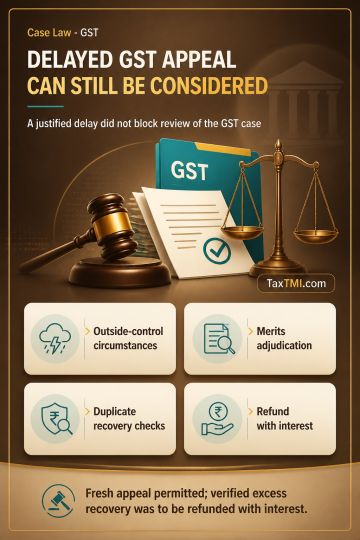
GST appellate limitation bound the Appellate Authority, but delay caused by circumstances beyond the taxpayer's control was treated as sufficient cause for condonation to prevent prejudice from denial of a merits hearing. A fresh statutory appeal could therefore be filed within the permitted period for adjudication on merits. Alleged duplicate recovery of GST demand required verification rather than an immediate factual finding; any excess recovery identified on verification was to be refunded with applicable interest.
GST appellate limitation bound the Appellate Authority, but delay caused by circumstances beyond the taxpayer's control was treated as sufficient cause for condonation to prevent prejudice from denial of a merits hearing. A fresh statutory appeal could therefore be filed within the permitted period for adjudication on merits. Alleged duplicate recovery of GST demand required verification rather than an immediate factual finding; any excess recovery identified on verification was to be refunded with applicable interest.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI