Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
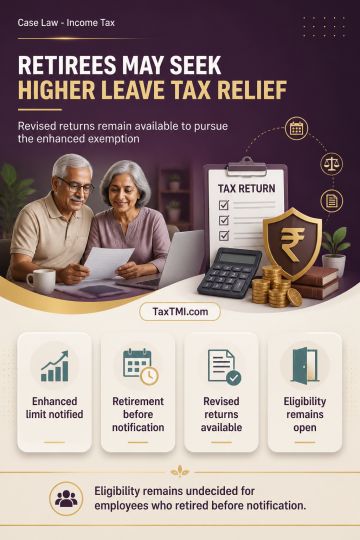
Enhanced exemption for leave encashment under section 10(10AA)(ii), notified with effect from 1 April 2023, is claimed by retired employees who superannuated before the notification came into force. Since the petitions were filed before expiry of the period for filing revised returns, the employees may pursue revised returns and other remedies available under the Act. Eligibility for the enhanced exemption, including its application to pre-notification superannuation, remains open for consideration in those proceedings.
Enhanced exemption for leave encashment under section 10(10AA)(ii), notified with effect from 1 April 2023, is claimed by retired employees who superannuated before the notification came into force. Since the petitions were filed before expiry of the period for filing revised returns, the employees may pursue revised returns and other remedies available under the Act. Eligibility for the enhanced exemption, including its application to pre-notification superannuation, remains open for consideration in those proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918