Tariff rate quota authorisations govern preferential imports of specified New Zealand goods through export certification and electronic customs debiti...
Electronic Continuity Bond Registration replaces manual container permissions, with quarterly reporting and re-export monitoring for duty-free contain...
Delayed transport documents failed to validate intercepted goods, sustaining transit-state penalties where the claimed interstate destination remained...
Section 12AB(4) requires an inquiry and satisfaction of a...
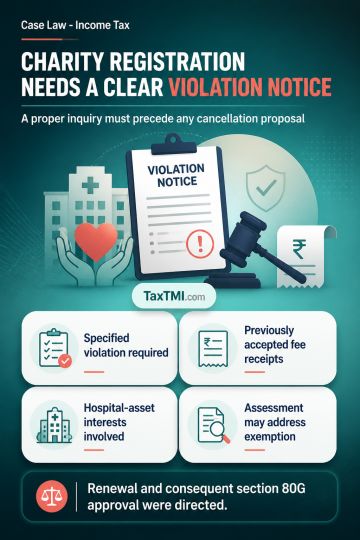
Charitable trust registration requires a specified-violation notice; settled cash deposits and related-party payments did not justify cancellation or renewal refusal.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Section 12AB(4) requires an inquiry and satisfaction of a specified violation before a notice proposing cancellation of charitable-trust registration. A notice must identify the statutory basis and alleged violation, and must give a reasonable opportunity to respond; failure to do so renders cancellation and refusal of renewal unsustainable. Cash deposits during demonetisation could not support non-genuineness where they had already been accepted as reported fee receipts. Related-party payments connected with protecting hospital-asset interests did not establish diversion of funds or a non-genuine activity. A section 13(1)(c) issue is not itself a specified violation for cancellation and may instead affect exemption at assessment. Renewal and consequent section 80G approval were directed.
Section 12AB(4) requires an inquiry and satisfaction of a specified violation before a notice proposing cancellation of charitable-trust registration. A notice must identify the statutory basis and alleged violation, and must give a reasonable opportunity to respond; failure to do so renders cancellation and refusal of renewal unsustainable. Cash deposits during demonetisation could not support non-genuineness where they had already been accepted as reported fee receipts. Related-party payments connected with protecting hospital-asset interests did not establish diversion of funds or a non-genuine activity. A section 13(1)(c) issue is not itself a specified violation for cancellation and may instead affect exemption at assessment. Renewal and consequent section 80G approval were directed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI