Bogus-purchase additions are limited to embedded profit where corresponding sales are accepted, while accommodation-entry information can support reas...
Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
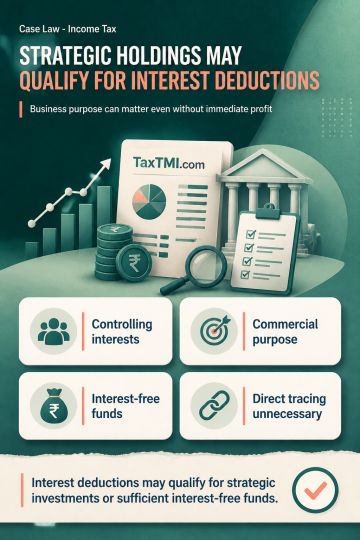
Interest on borrowings used to acquire or maintain controlling interests through strategic investments may qualify as business expenditure where the taxpayer's objects, investment pattern, conduct and disclosures establish that strategic investment is part of its business. The business-purpose requirement extends beyond immediate profit generation; dividend being taxed under another head or investments not producing direct business receipts does not by itself defeat deductibility where commercial expediency exists. Separately, where available interest-free funds exceed investments and interest-free advances, investments are presumed to have been made from those funds. Absence of a direct fund-wise nexus therefore does not justify disallowing interest on borrowings.
Interest on borrowings used to acquire or maintain controlling interests through strategic investments may qualify as business expenditure where the taxpayer's objects, investment pattern, conduct and disclosures establish that strategic investment is part of its business. The business-purpose requirement extends beyond immediate profit generation; dividend being taxed under another head or investments not producing direct business receipts does not by itself defeat deductibility where commercial expediency exists. Separately, where available interest-free funds exceed investments and interest-free advances, investments are presumed to have been made from those funds. Absence of a direct fund-wise nexus therefore does not justify disallowing interest on borrowings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921