Electronic evidence and search statements in tax assessments require authenticity review and corroboration, while procedural manuals lack statutory fo...
Tariff rate quota authorisations govern preferential imports of specified New Zealand goods through export certification and electronic customs debiti...
Electronic Continuity Bond Registration replaces manual container permissions, with quarterly reporting and re-export monitoring for duty-free contain...
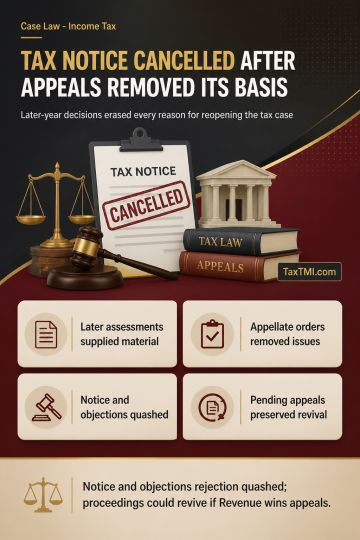
Reassessment founded on additions and disallowances in later assessment years lacks a subsisting basis where appellate orders for those years delete or decide in the assessee's favour every issue relied upon for reopening. Although later assessment orders may initially constitute material for reopening, the reasons to believe that income escaped assessment cease once their foundation is removed. The reassessment notice and rejection of objections were quashed, while other challenges remained open and proceedings could revive if the Revenue succeeds in pending appeals on a foundational issue.
Reassessment founded on additions and disallowances in later assessment years lacks a subsisting basis where appellate orders for those years delete or decide in the assessee's favour every issue relied upon for reopening. Although later assessment orders may initially constitute material for reopening, the reasons to believe that income escaped assessment cease once their foundation is removed. The reassessment notice and rejection of objections were quashed, while other challenges remained open and proceedings could revive if the Revenue succeeds in pending appeals on a foundational issue.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921