Tariff rate quota authorisations govern preferential imports of specified New Zealand goods through export certification and electronic customs debiti...
Electronic Continuity Bond Registration replaces manual container permissions, with quarterly reporting and re-export monitoring for duty-free contain...
Delayed transport documents failed to validate intercepted goods, sustaining transit-state penalties where the claimed interstate destination remained...
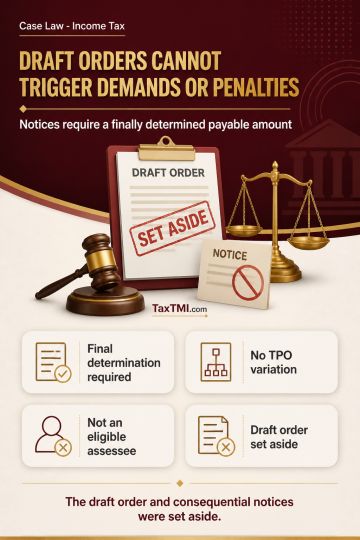
Demand and penalty-initiation notices cannot rest on an order expressly issued as a draft assessment order. Where proposed disallowances remain proposals, no demand or penalty notice is issued, and the taxpayer retains the right to accept variations or object before final assessment, the payable sum has not been finally determined. Such a defect is not a mere uploading error curable through Section 292B, especially without a subsequent corrective or clarificatory order. Draft assessment procedure is also unavailable where the Transfer Pricing Officer makes no variation to returned income from international transactions; the taxpayer is then not an eligible assessee under Section 144C. The draft order and consequential notices were set aside.
Demand and penalty-initiation notices cannot rest on an order expressly issued as a draft assessment order. Where proposed disallowances remain proposals, no demand or penalty notice is issued, and the taxpayer retains the right to accept variations or object before final assessment, the payable sum has not been finally determined. Such a defect is not a mere uploading error curable through Section 292B, especially without a subsequent corrective or clarificatory order. Draft assessment procedure is also unavailable where the Transfer Pricing Officer makes no variation to returned income from international transactions; the taxpayer is then not an eligible assessee under Section 144C. The draft order and consequential notices were set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI