Section 270AA penalty immunity requires identified statutory defaults and a hearing before rejection; reassessment disclosure may constitute under-rep...
Section 80JJAA employee-cost deduction allowed for deployed staff but barred against transfer-pricing income enhancement, with pricing issues remanded...
Transfer-pricing methodology protects commercially genuine associated-enterprise payments, while pre-2016 secondary adjustments and related notional i...
Negative liens over operating assets can constitute international transactions requiring arm's-length pricing reflecting restricted borrowing and expa...
Cross-examination rights in Customs Broker revocation inquiries require witness examination; procedural denial may be cured through fresh adjudication...
Transfer-pricing comparability for sourcing support services...
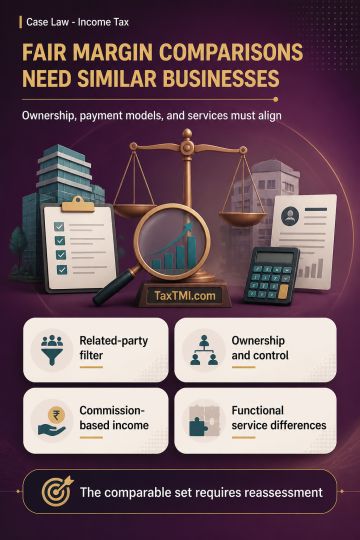
Transfer-pricing comparability requires aligned related-party exposure, ownership profile, revenue model and sourcing-support functions to prevent distorted margins in benchmark analysis.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Transfer-pricing comparability for sourcing support services requires consistent application of the related-party transaction filter and exclusion of entities that fail it. Government-owned undertakings may not be suitable comparables where their ownership and control distinguish them from the tested party. A commission-based enterprise is not comparable with a cost-plus service provider because commission income depends on orders materialising, while cost-plus remuneration provides a mark-up on costs irrespective of sales. Project-management, infrastructure, engineering, architectural, and sector-specific consultancy services may also be functionally dissimilar to sourcing support services, requiring reassessment of the comparable set.
Transfer-pricing comparability for sourcing support services requires consistent application of the related-party transaction filter and exclusion of entities that fail it. Government-owned undertakings may not be suitable comparables where their ownership and control distinguish them from the tested party. A commission-based enterprise is not comparable with a cost-plus service provider because commission income depends on orders materialising, while cost-plus remuneration provides a mark-up on costs irrespective of sales. Project-management, infrastructure, engineering, architectural, and sector-specific consultancy services may also be functionally dissimilar to sourcing support services, requiring reassessment of the comparable set.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921