Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
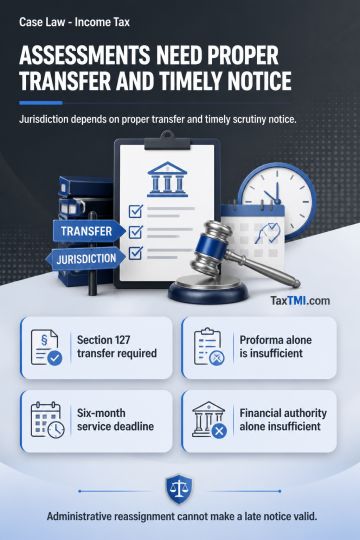
Assessment jurisdiction depends on a valid statutory transfer where scrutiny proceedings move between Assessing Officers. An administrative proforma, without a transfer order under section 127, does not confer jurisdiction on the successor officer, even where that officer has pecuniary jurisdiction. Scrutiny notice validity also depends on service within six months from the end of the financial year in which the return is furnished under section 143(2). A notice issued after that period cannot be treated as valid merely because proceedings were administratively transferred. These requirements determine whether assessment proceedings can be sustained.
Assessment jurisdiction depends on a valid statutory transfer where scrutiny proceedings move between Assessing Officers. An administrative proforma, without a transfer order under section 127, does not confer jurisdiction on the successor officer, even where that officer has pecuniary jurisdiction. Scrutiny notice validity also depends on service within six months from the end of the financial year in which the return is furnished under section 143(2). A notice issued after that period cannot be treated as valid merely because proceedings were administratively transferred. These requirements determine whether assessment proceedings can be sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918