Section 270AA penalty immunity requires identified statutory defaults and a hearing before rejection; reassessment disclosure may constitute under-rep...
Section 80JJAA employee-cost deduction allowed for deployed staff but barred against transfer-pricing income enhancement, with pricing issues remanded...
Transfer-pricing methodology protects commercially genuine associated-enterprise payments, while pre-2016 secondary adjustments and related notional i...
Negative liens over operating assets can constitute international transactions requiring arm's-length pricing reflecting restricted borrowing and expa...
Cross-examination rights in Customs Broker revocation inquiries require witness examination; procedural denial may be cured through fresh adjudication...
Penalty proceedings under section 271D for accepting cash loans...
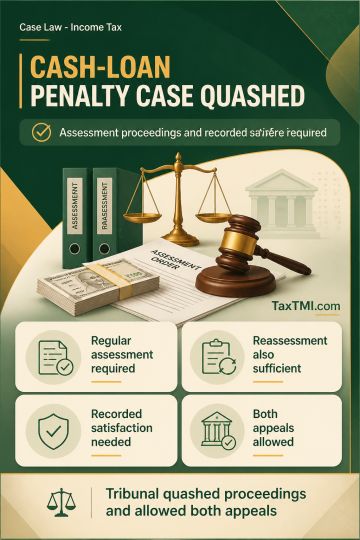
Penalty proceedings for cash-loan acceptance require assessment proceedings and recorded Assessing Officer satisfaction; absent these, the proceedings were quashed.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Penalty proceedings under section 271D for accepting cash loans contrary to section 269SS require a regular assessment or reassessment and the Assessing Officer's recorded satisfaction of the alleged contravention. Where neither scrutiny assessment nor reassessment had commenced and no satisfaction was recorded, the Tribunal quashed the proceedings. The approach follows High Court precedent that, without a regular assessment, recourse to comparable penalty proceedings under section 271E is unjustified. Both appeals were allowed.
Penalty proceedings under section 271D for accepting cash loans contrary to section 269SS require a regular assessment or reassessment and the Assessing Officer's recorded satisfaction of the alleged contravention. Where neither scrutiny assessment nor reassessment had commenced and no satisfaction was recorded, the Tribunal quashed the proceedings. The approach follows High Court precedent that, without a regular assessment, recourse to comparable penalty proceedings under section 271E is unjustified. Both appeals were allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920