Section 270AA penalty immunity requires identified statutory defaults and a hearing before rejection; reassessment disclosure may constitute under-rep...
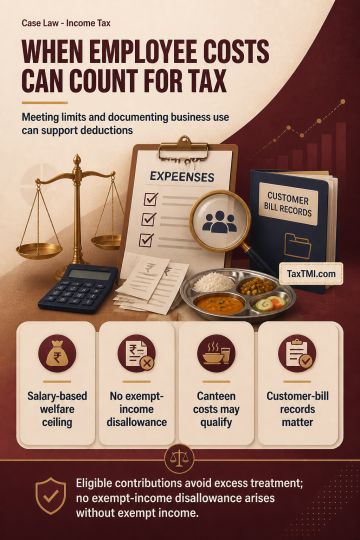
Section 80JJAA employee-cost deduction allowed for deployed staff but barred against transfer-pricing income enhancement, with pricing issues remanded...
Transfer-pricing methodology protects commercially genuine associated-enterprise payments, while pre-2016 secondary adjustments and related notional i...
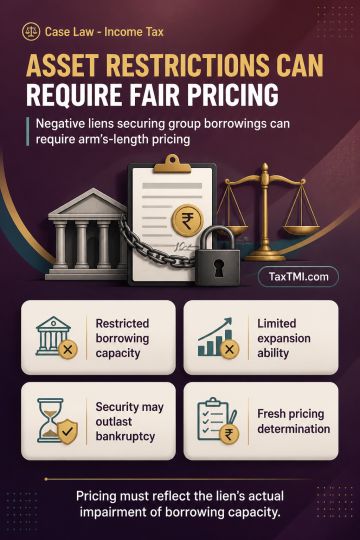
Negative liens over operating assets can constitute international transactions requiring arm's-length pricing reflecting restricted borrowing and expa...
Cross-examination rights in Customs Broker revocation inquiries require witness examination; procedural denial may be cured through fresh adjudication...
TDS-default proceedings concerning commission paid to travel agents require verification of the actual commission amount and the tax-deduction obligation on payments to foreign agents without a permanent establishment in India. Although the appellate authority treated the objections as directed at the original TDS-default order rather than the rectification order, the rectification record included the assessee's submission that tax had already been deducted on part of the commission. The Tribunal restored the matter to the Assessing Officer for fresh verification, after a final opportunity for the assessee to substantiate its commission claim, and for decision in accordance with law.
TDS-default proceedings concerning commission paid to travel agents require verification of the actual commission amount and the tax-deduction obligation on payments to foreign agents without a permanent establishment in India. Although the appellate authority treated the objections as directed at the original TDS-default order rather than the rectification order, the rectification record included the assessee's submission that tax had already been deducted on part of the commission. The Tribunal restored the matter to the Assessing Officer for fresh verification, after a final opportunity for the assessee to substantiate its commission claim, and for decision in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920