Charitable character assessment preserves Section 80G approval despite inclusive spiritual teachings and incidental religious expenditure within the s...
Penalty proceedings for cash-loan acceptance require assessment proceedings and recorded Assessing Officer satisfaction; absent these, the proceedings...
Functional comparability governs software-service benchmarking: dissimilar companies are excluded, while related-party filters, margins and working-ca...
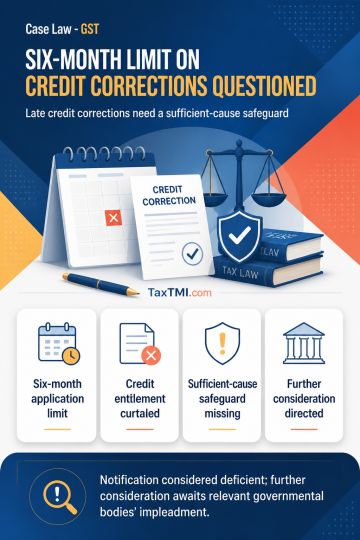
The six-month application period for rectifying orders denying input tax credit was questioned as an impermissible restriction on statutory entitlement. Although the Government may prescribe a special procedure for input tax credit, that power must include conditions and safeguards protecting taxpayers. The amended provision made credit available for returns filed by the stipulated date but did not impose an application deadline. A procedure that bars relief after six months without allowing extension where sufficient cause prevented timely application curtails the accrued right to credit. The notification was considered deficient for lacking such a safeguard, with further consideration directed after impleadment of relevant governmental bodies.
The six-month application period for rectifying orders denying input tax credit was questioned as an impermissible restriction on statutory entitlement. Although the Government may prescribe a special procedure for input tax credit, that power must include conditions and safeguards protecting taxpayers. The amended provision made credit available for returns filed by the stipulated date but did not impose an application deadline. A procedure that bars relief after six months without allowing extension where sufficient cause prevented timely application curtails the accrued right to credit. The notification was considered deficient for lacking such a safeguard, with further consideration directed after impleadment of relevant governmental bodies.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918