Tariff rate quota authorisations govern preferential imports of specified New Zealand goods through export certification and electronic customs debiti...
Electronic Continuity Bond Registration replaces manual container permissions, with quarterly reporting and re-export monitoring for duty-free contain...
Delayed transport documents failed to validate intercepted goods, sustaining transit-state penalties where the claimed interstate destination remained...
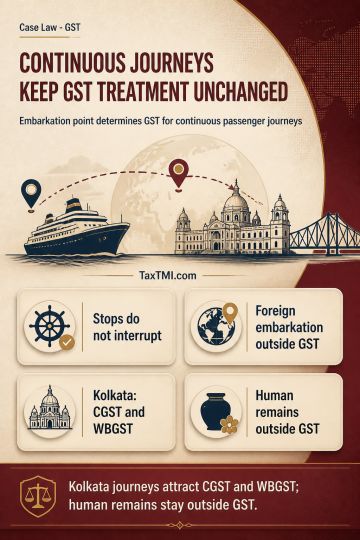
Passenger transportation follows the place of embarkation for a continuous journey. Where either the supplier or passenger is outside India, a short transit stop does not amount to a stopover or interrupt the journey; transportation embarking outside India consequently has a place of supply outside India and is not subject to GST. Where both supplier and passenger are in India, embarkation from Kolkata makes the service an intra-State supply liable to CGST and WBGST at the notified rate, with economy-class treatment subject to the input tax credit condition. Air transportation of human remains falls within funeral, burial, crematorium or mortuary services and is neither a supply of goods nor services, so remains outside GST.
Passenger transportation follows the place of embarkation for a continuous journey. Where either the supplier or passenger is outside India, a short transit stop does not amount to a stopover or interrupt the journey; transportation embarking outside India consequently has a place of supply outside India and is not subject to GST. Where both supplier and passenger are in India, embarkation from Kolkata makes the service an intra-State supply liable to CGST and WBGST at the notified rate, with economy-class treatment subject to the input tax credit condition. Air transportation of human remains falls within funeral, burial, crematorium or mortuary services and is neither a supply of goods nor services, so remains outside GST.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI