Electronic certificates of origin enable preferential tariffs under the India-New Zealand FTA when format, verification, and filing requirements are m...
Customs approval for liquid cargo exports extends designated jetty operations while existing boarding station and customs area limits remain unchanged...
Mandatory compliance document verification now conditions out-of-charge clearance for imported cosmetics, drugs, and medical devices through PGA-facil...
Double taxation of turnover requires holistic verification across separately registered units and permits limited rectification of overlapping assessm...
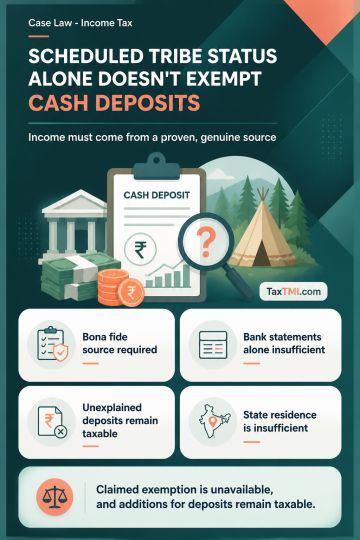
Scheduled Tribe income exemption applies only where the taxpayer establishes income from a valid, bona fide source within the statutory conditions. Cash deposits treated as unexplained money do not become exempt solely because the taxpayer is a Scheduled Tribe member residing in a specified State. Bank statements, without books of account or other evidence establishing the source, are insufficient to prove the character of deposits. Consequently, additions for unexplained cash deposits remain taxable and the claimed exemption is unavailable.
Scheduled Tribe income exemption applies only where the taxpayer establishes income from a valid, bona fide source within the statutory conditions. Cash deposits treated as unexplained money do not become exempt solely because the taxpayer is a Scheduled Tribe member residing in a specified State. Bank statements, without books of account or other evidence establishing the source, are insufficient to prove the character of deposits. Consequently, additions for unexplained cash deposits remain taxable and the claimed exemption is unavailable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI