Electronic certificates of origin enable preferential tariffs under the India-New Zealand FTA when format, verification, and filing requirements are m...
Customs approval for liquid cargo exports extends designated jetty operations while existing boarding station and customs area limits remain unchanged...
Mandatory compliance document verification now conditions out-of-charge clearance for imported cosmetics, drugs, and medical devices through PGA-facil...
Double taxation of turnover requires holistic verification across separately registered units and permits limited rectification of overlapping assessm...
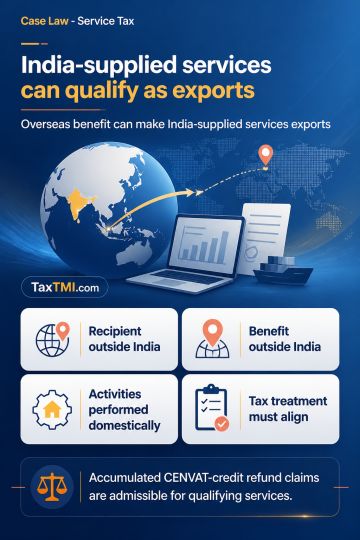
Revenue cannot treat Business Auxiliary Services supplied to a foreign recipient as non-exported for Rule 5 CENVAT-credit refund purposes while not seeking recovery of service tax on the inconsistent premise that those same services were taxable in India. Category III services supplied in relation to business or commerce qualify as exports where the recipient is outside India and the benefit accrues outside India, even if activities are performed in India. Accumulated CENVAT-credit refund claims are therefore admissible for qualifying services.
Revenue cannot treat Business Auxiliary Services supplied to a foreign recipient as non-exported for Rule 5 CENVAT-credit refund purposes while not seeking recovery of service tax on the inconsistent premise that those same services were taxable in India. Category III services supplied in relation to business or commerce qualify as exports where the recipient is outside India and the benefit accrues outside India, even if activities are performed in India. Accumulated CENVAT-credit refund claims are therefore admissible for qualifying services.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI