Electronic evidence and search statements in tax assessments require authenticity review and corroboration, while procedural manuals lack statutory fo...
Tariff rate quota authorisations govern preferential imports of specified New Zealand goods through export certification and electronic customs debiti...
Electronic Continuity Bond Registration replaces manual container permissions, with quarterly reporting and re-export monitoring for duty-free contain...
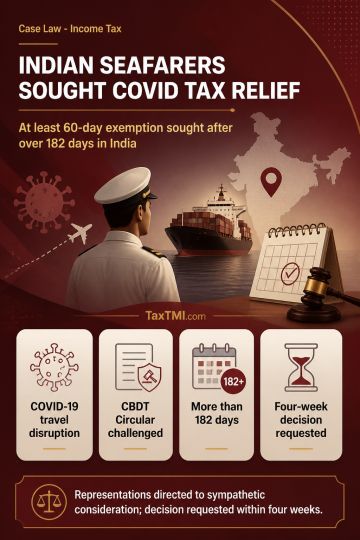
Tax-residency relief for Indian seafarers unable to remain outside India during the COVID-19 pandemic was sought through quashing CBDT Circular No. 11 of 2020 and adoption of a compassionate tax policy. The proposed policy would grant at least sixty days' exemption to seafarers who spent more than 182 days in India during a financial year. Representations were directed to receive sympathetic consideration, with an appropriate decision requested within four weeks, without examination of merits.
Tax-residency relief for Indian seafarers unable to remain outside India during the COVID-19 pandemic was sought through quashing CBDT Circular No. 11 of 2020 and adoption of a compassionate tax policy. The proposed policy would grant at least sixty days' exemption to seafarers who spent more than 182 days in India during a financial year. Representations were directed to receive sympathetic consideration, with an appropriate decision requested within four weeks, without examination of merits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921