Electronic certificates of origin enable preferential tariffs under the India-New Zealand FTA when format, verification, and filing requirements are m...
Customs approval for liquid cargo exports extends designated jetty operations while existing boarding station and customs area limits remain unchanged...
Mandatory compliance document verification now conditions out-of-charge clearance for imported cosmetics, drugs, and medical devices through PGA-facil...
Page of 4921
Press 'Enter' after typing page number.
1 to 20 of 98414 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
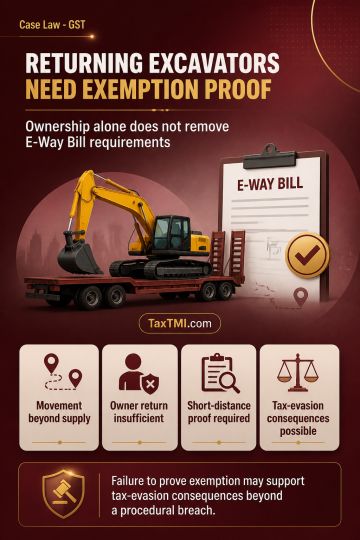
E-Way Bill requirements extend to movement of goods for reasons other than supply, including return of an excavator from a work site to registered premises. Ownership and return to the owner's premises do not independently remove that requirement. A short-distance exemption must be established with satisfactory evidence that the movement falls within Rule 138(14) or an applicable notification. Failure to prove the exemption, or to clarify the tax treatment of consideration for use of the equipment, may prevent the breach from being treated as merely procedural and may support tax-evasion consequences under CGST/UPGST enforcement provisions.
E-Way Bill requirements extend to movement of goods for reasons other than supply, including return of an excavator from a work site to registered premises. Ownership and return to the owner's premises do not independently remove that requirement. A short-distance exemption must be established with satisfactory evidence that the movement falls within Rule 138(14) or an applicable notification. Failure to prove the exemption, or to clarify the tax treatment of consideration for use of the equipment, may prevent the breach from being treated as merely procedural and may support tax-evasion consequences under CGST/UPGST enforcement provisions.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI