Electronic certificates of origin enable preferential tariffs under the India-New Zealand FTA when format, verification, and filing requirements are m...
Customs approval for liquid cargo exports extends designated jetty operations while existing boarding station and customs area limits remain unchanged...
Mandatory compliance document verification now conditions out-of-charge clearance for imported cosmetics, drugs, and medical devices through PGA-facil...
Double taxation of turnover requires holistic verification across separately registered units and permits limited rectification of overlapping assessm...
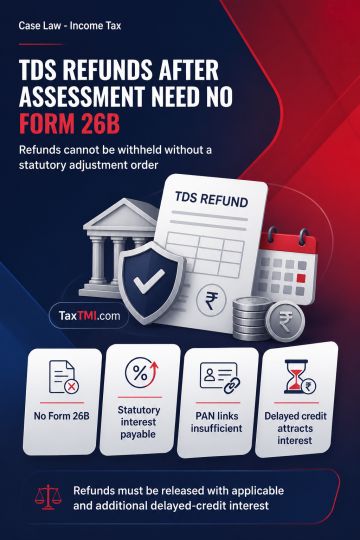
Refunds arising from TDS assessments under section 201 or appellate orders constitute crystallised entitlements payable with statutory interest, without requiring Form 26B. Section 200A, Rule 31A and Form 26B govern CPC processing and adjustment of TDS before assessment and do not apply to post-assessment refunds. Such refunds may be withheld or set off against outstanding demands only through a statutory adjustment order under section 245; demands linked to the taxpayer's PAN or related TANs alone do not justify withholding. The Department was directed to release the refunds with applicable interest, with additional interest for delayed credit.
Refunds arising from TDS assessments under section 201 or appellate orders constitute crystallised entitlements payable with statutory interest, without requiring Form 26B. Section 200A, Rule 31A and Form 26B govern CPC processing and adjustment of TDS before assessment and do not apply to post-assessment refunds. Such refunds may be withheld or set off against outstanding demands only through a statutory adjustment order under section 245; demands linked to the taxpayer's PAN or related TANs alone do not justify withholding. The Department was directed to release the refunds with applicable interest, with additional interest for delayed credit.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI