Loading...

Top
Help
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback

Contact Us At :

E-mail: [email protected]

Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
Add to...
You have not created any category. Kindly create one to bookmark this item!
Create New Category
Hide
Title :
Description :
❮❮ Hide
Default View
Expand ❯❯
Close ✕
🔎 Highlights - Adv. Search
TEXT SEARCH:

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In:
Main Text + AI Text
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws----
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ----
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ----
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
    Show cause notice and hearing are mandatory before penalty, making an unnotified penalty unsustainable for natural justice breach.
    Duplicate input tax credit demands cannot target identical supplier transactions, while proceedings concerning distinct suppliers remain available.
    Jurisdictional facts in certificate-of-origin discrepancies can support customs show-cause proceedings, leaving factual explanations for departmental ...
    Specific grounds in GST cancellation notices are essential; cancellation based on an unnotified ground was quashed and registration restored.
    Statutory appellate remedy for GST registration cancellation limits writ jurisdiction despite an unconsidered revocation representation.
    Extended input tax credit timelines protect delayed returns filed before the statutory cut-off, subject to documentary eligibility.
    Occupancy Certificate determines project completion, preserving GST credit benefit restitution for identifiable homebuyers while barring retrospective...
    Interest wrongly classified as tax cannot require GST appellate pre-deposit; the appeal must be reconsidered on merits.
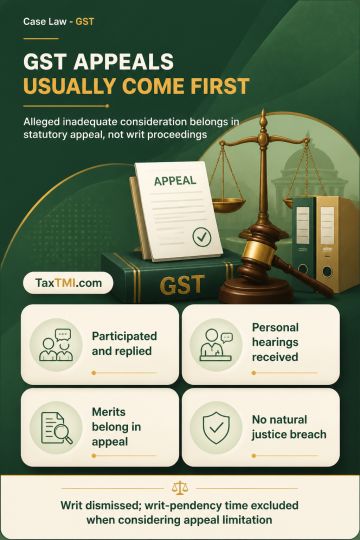
    Statutory GST appeal remedy prevails where alleged inadequate consideration of replies does not establish a natural justice breach.
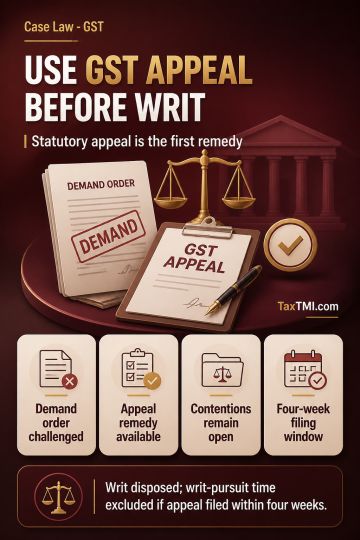
    Statutory GST appellate remedy must be pursued before writ review of a demand order, with limitation protection granted.
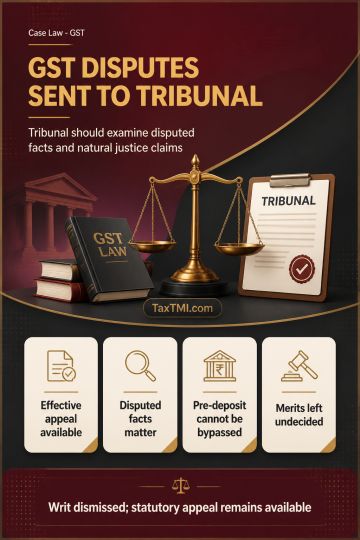
    Efficacious GST appellate remedy bars writ review where disputed factual issues and statutory pre-deposit must be addressed by the Tribunal.
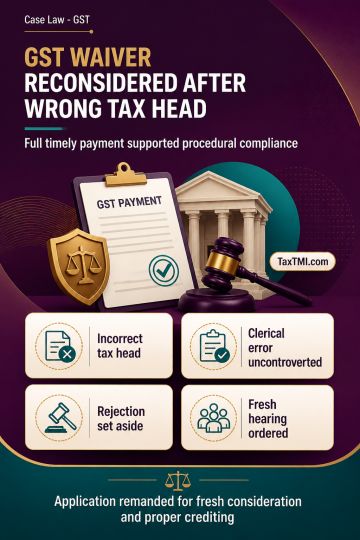
    Substantial procedural compliance supports GST waiver reconsideration where full tax was timely paid under an incorrect tax head.
    Consequential GST refund rejection requires statutory appeal where fresh lawful grounds remain open after appellate remand.
    GST adjudication order issuance within limitation remains valid despite later portal upload, which concerns service and enforceability.
    Alternative statutory appeal remedy bars writ challenge to ineligible input tax credit demand based on alleged fake invoices.
    Binding effect of advance rulings excludes supply recipients, leaving contractual GST reimbursement insufficient to establish writ standing.
    Duplicative GST adjudication for the same issues and assessment period invalidates subsequent State GST assessment and rectification orders.
    Statutory GST liability overrides works-contract reimbursement disputes, limiting contractual claims and barring non-statutory return or waiver relief...
    E-way bill compliance applies to machinery returned for testing under delivery challans, despite no taxable supply arising.
    Excess input tax credit beyond reflected supplier data attracts extended-period assessment, interest and penalty; turnover mismatch requires documenta...
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Showing Results for : Reset Filters

Topics

Acts Income Tax