Section 91 CrPC requires necessary search records; witness recall fails without evidence essential to a just decision.
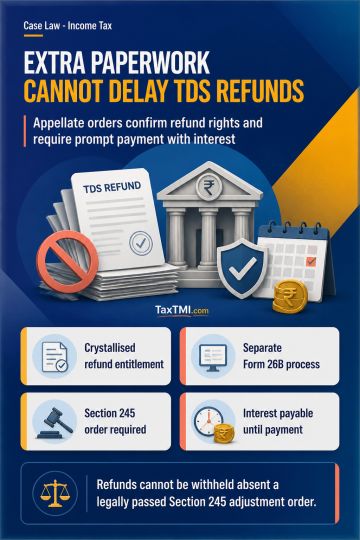
TDS refund entitlement under appellate give-effect orders cannot be deferred by post-assessment technical requirements alone.
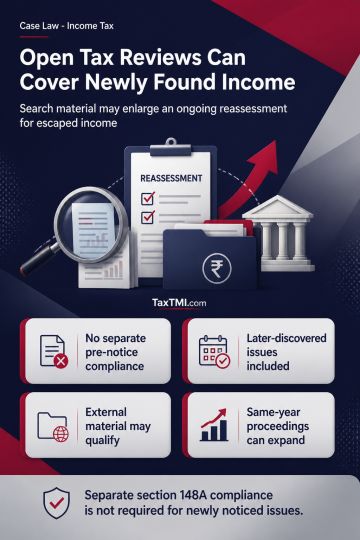
Subsequently noticed escaped income permits enlargement of pending reassessment using search material without separate pre-notice compliance.
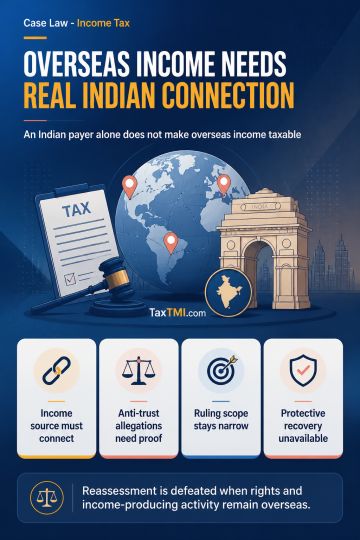
Income accrual for non-residents requires a real Indian nexus, defeating reassessment where rights and activity are overseas.
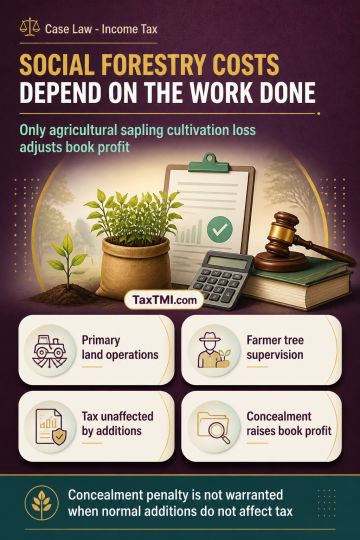
Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
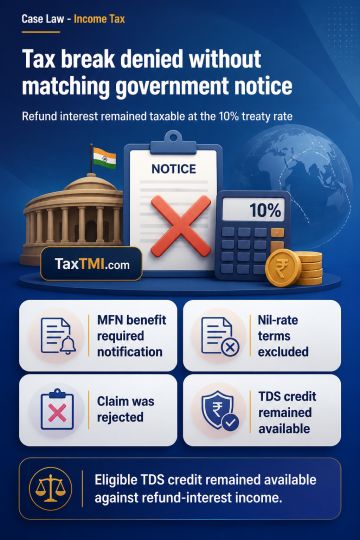
MFN treaty benefits require specific domestic notification, leaving tax refund interest taxable at the Netherlands treaty interest rate.
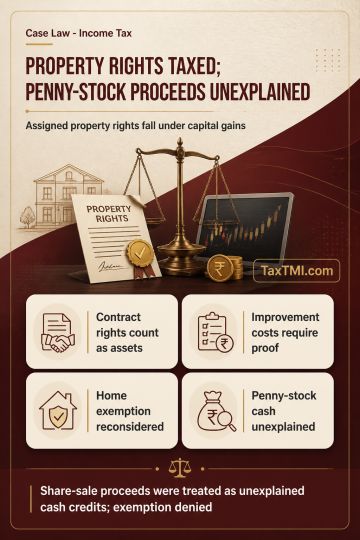
Assignment of contractual property rights attracts capital gains, while penny-stock sale proceeds may be taxed as unexplained cash credits
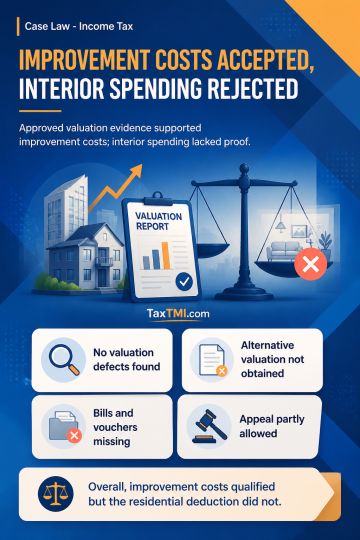
Approved valuation reports support improvement-cost claims, while unsupported interior spending cannot qualify for residential reinvestment relief.
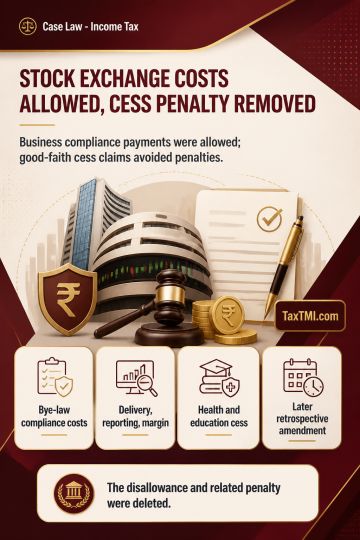
Stock exchange compliance charges qualify as deductible business expenditure; bona fide cess claims cannot trigger under-reporting penalties.
Inaccurate-particulars penalties fail where transfer-pricing documentation shows good faith and due diligence, and underlying capital-gains additions ...
Form No. 9A timing remains prospective, while charitable trusts retain independent statutory accumulation within the permissible limit.
Revised tax audit reports filed before processing require consideration, preventing duplicate tax-withholding disallowances after payer compliance ver...
Section 12AB registration scope protects charitable hospitals despite overseas training, fee-based care, surplus, and disputed regulatory compliance.
Intra-group service benefit evidence prevents nil pricing, while associated-enterprise receivables require LIBOR-based interest benchmarking after the...
Entity-level transfer pricing benchmarking required where interlinked trading and manufacturing transactions cannot be reliably segmented.
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verificatio...
Form No. 98 reporting introduces mandatory online registration, digital filing, corrections, deletion statements, and information security controls.
Wrongful Principal Officer Designation Invalidates TDS Prosecution Where the Accused Was Never a Company Director
Clean-slate protection bars reassessment based on extinguished liabilities and prevents repeated taxation of the same alleged income.
Mixed charitable and religious trust objects permit fresh consideration of tax-deduction approval where public benefit predominates.
 TaxTMI
 TaxTMI

 of 1978