Transfer pricing comparability requires turnover and functional analysis, alongside rules on exempt-income disallowance and amalgamation goodwill depr...
Complainant participation in insolvency disciplinary appeals is not automatically mandatory, while later representative changes do not undo valid acts...
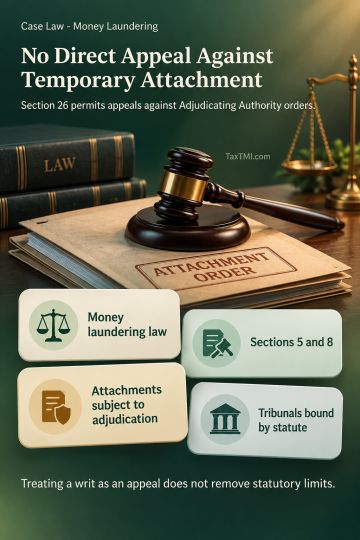
Direct appeals against provisional attachment under money laundering law fall outside appellate jurisdiction, which covers adjudicating authority orde...
Cross-border secondment reimbursements require separate employment and knowledge-transfer analysis before taxation as included services under the Indi...
Writ jurisdiction may be exercised against show cause notices...
Writ relief against show cause notices is available where jurisdiction is absent and concluded advance rulings cannot be reopened without fresh fraud evidence.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Writ jurisdiction may be exercised against show cause notices where the notice is alleged to be without jurisdiction, pre-determined, or abusive, even if alternative statutory remedies exist. The Court treated the challenge as one to the very assumption of power and rejected objections of prematurity and disputed facts. It further held that advance rulings are binding on the applicant and jurisdictional officer unless law or facts change, and that reopening the same issues requires fresh material showing fraud, wilful misstatement, or suppression. As no such material existed and the earlier adjudication had attained finality, the notices under the GST and excise laws were held to be without jurisdiction and quashed.
Writ jurisdiction may be exercised against show cause notices where the notice is alleged to be without jurisdiction, pre-determined, or abusive, even if alternative statutory remedies exist. The Court treated the challenge as one to the very assumption of power and rejected objections of prematurity and disputed facts. It further held that advance rulings are binding on the applicant and jurisdictional officer unless law or facts change, and that reopening the same issues requires fresh material showing fraud, wilful misstatement, or suppression. As no such material existed and the earlier adjudication had attained finality, the notices under the GST and excise laws were held to be without jurisdiction and quashed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI

 of 4949









 Get Daily Updates


