Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
Retrospective invalidity of ocean-freight IGST supports refunds despite non-party status and prior credit utilisation, subject to authorised appeal gr...
Additional evidence in departmental appeals may include show-cause-notice material without introducing a new case where it merely corroborates existin...
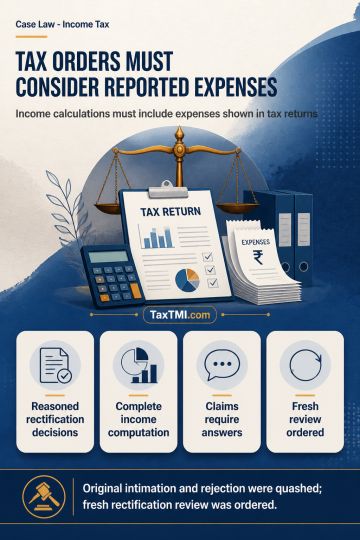
Reasoned rectification orders require consideration of expenditure disclosed in income-tax returns, preventing revision based on incomplete income com...
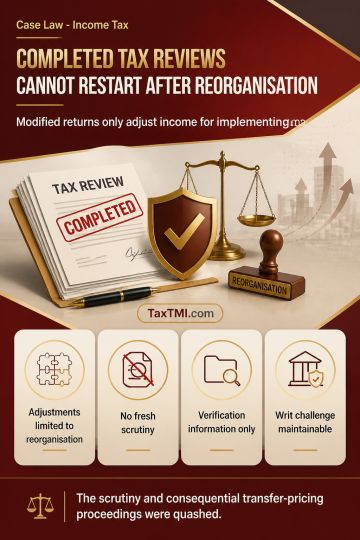
Modified returns after business reorganisations cannot trigger fresh scrutiny once the original assessment was complete, invalidating related transfer...
Page of 4891
Press 'Enter' after typing page number.
21 to 40 of 97820 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Challenge to search and seizure under the CGST regime centred on whether cash qualifies as "goods" or as "documents or books or things" under Section 67; the court held the statutory definition of goods excludes money and reading "things" ejusdem generis with "documents" and "books" limits it to evidentiary items containing information. Cash may be seized only where specific notes or currency can be shown to have direct evidentiary value traceable to taxable transactions. On the facts, authorities failed to establish evidentiary necessity; the cash was ordered de-sealed and released, while broader validity of the search was left for further affidavit exchange and hearing with interim procedural restraints.
Challenge to search and seizure under the CGST regime centred on whether cash qualifies as "goods" or as "documents or books or things" under Section 67; the court held the statutory definition of goods excludes money and reading "things" ejusdem generis with "documents" and "books" limits it to evidentiary items containing information. Cash may be seized only where specific notes or currency can be shown to have direct evidentiary value traceable to taxable transactions. On the facts, authorities failed to establish evidentiary necessity; the cash was ordered de-sealed and released, while broader validity of the search was left for further affidavit exchange and hearing with interim procedural restraints.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891