Retrospective invalidity of ocean-freight IGST supports refunds despite non-party status and prior credit utilisation, subject to authorised appeal gr...
Additional evidence in departmental appeals may include show-cause-notice material without introducing a new case where it merely corroborates existin...
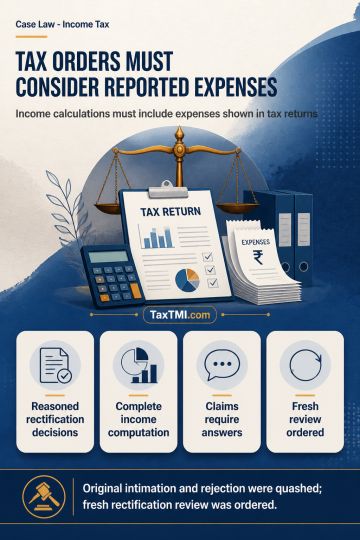
Reasoned rectification orders require consideration of expenditure disclosed in income-tax returns, preventing revision based on incomplete income com...
Modified returns after business reorganisations cannot trigger fresh scrutiny once the original assessment was complete, invalidating related transfer...
Third-party loose sheets require reliable nexus before supporting unexplained expenditure additions; presumptions do not establish payer identity or o...
TNMM comparability using audited accounts and working-capital adjustments can eliminate unwarranted transfer-pricing additions where verified margins ...
Gross-profit additions on disputed purchases require reasoned appellate determination; disclosed claims alone do not support inaccurate-particulars pe...
The article addresses validity of cash seizures under the CGST framework, holding that seizure under the statute requires a recorded 'reason to believe' that goods, documents, books or things relevant to proceedings are secreted at a place; absence of such reasons rendered the cash seizure arbitrary and unlawful. It further explains that failure to issue the statutorily mandated notice within the six month period obliges return of seized items, and that transferring seized cash to another agency without statutory authority compounds illegality; consequent remedy ordered was release and payment with interest.
The article addresses validity of cash seizures under the CGST framework, holding that seizure under the statute requires a recorded 'reason to believe' that goods, documents, books or things relevant to proceedings are secreted at a place; absence of such reasons rendered the cash seizure arbitrary and unlawful. It further explains that failure to issue the statutorily mandated notice within the six month period obliges return of seized items, and that transferring seized cash to another agency without statutory authority compounds illegality; consequent remedy ordered was release and payment with interest.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921