Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Composite car radio-DVD classification requires proof of principal function; indeterminacy places goods under the last equally meriting heading.
    Liquidation auction value governs stamp duty when transparent insolvency sales establish true market value for registration.
    Administrative write-down authority cannot be implied after a reconstruction scheme omits specific AT-1 bond powers.
    Customs clearance at Mandalgarh now covers unloading imported goods and loading export goods at the designated location.
    Financial Default Determination: Information Utility records and contemporaneous evidence support CIRP admission despite profitability disputes.
    Deemed withdrawal of GST best-judgment assessments follows delayed GSTR-3B filing when the requisite late fee is paid.
    Statutory GST liability prevails over works-contract terms, leaving VAT-to-GST reimbursement claims for resolution against employers.
    GST Payment Timing: Cash Ledger credit ends interest accrual, while late post-notice payment attracts mandatory penalty.
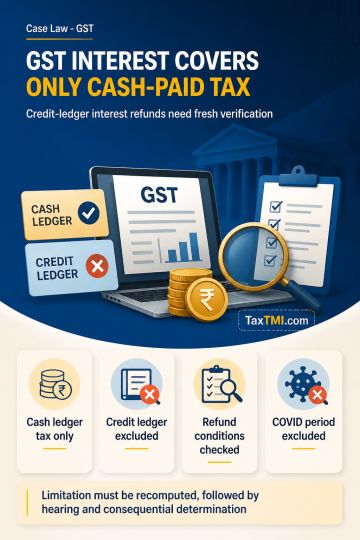
    Retrospective GST interest liability confines delayed-payment interest to cash-ledger tax, requiring reassessment of credit-ledger interest refunds.
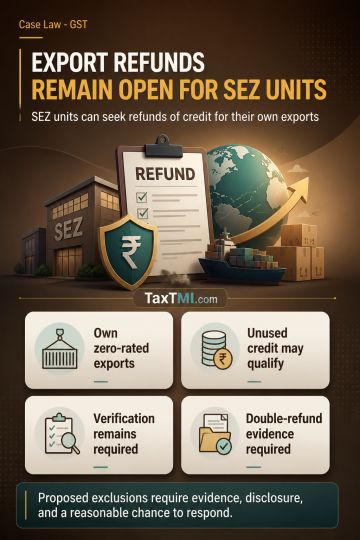
    ISD-distributed input tax credit refunds remain available to SEZ units for their own zero-rated exports, subject to verification.
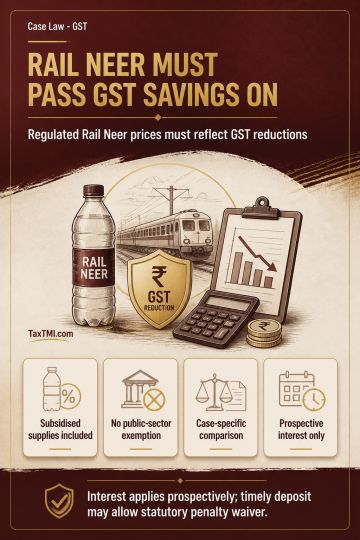
    Anti-profiteering obligations apply to regulated Rail Neer transfer prices, requiring GST benefits to reach recipients despite price controls.
    Bill-to/Ship-to E-Way Bills permit direct dispatch where the person causing movement generates compliant transport documentation.
    Road restoration charges constitute taxable Government services, triggering reverse charge and defeating claims of governmental-function exemption.
    Cumulative GST appellate pre-deposit permits prior deposits against the same demand, eliminating duplicate payment where statutory thresholds are met.
    Revision for inadequate enquiry may stand where assessment fails to test present liability against future obligation.
    Document Identification Number compliance renders TDS-default orders invalid where mandatory DIN requirements are breached and curative provision does...
    GST assessment without verified turnover required fresh manual rectification review, while coercive recovery remained barred pending reconsideration.
    Statutory limitation for GST detention penalties makes delayed orders jurisdictionally invalid despite an available appellate remedy.
    Retrospective input tax credit regularisation protects delayed returns filed by the prescribed cut-off from denial solely for lateness.
    Nil valuation of unbilled head office services prevents GST demands based on proportionate allocation of common expenditure.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Failure to conduct enquiries which ought to have been made...

Failure of enquiry: omission to verify prior year treatment and dealer arrangements rendered assessments erroneous and subject to revision.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Income Tax February 20, 2026 Case Laws AT
Failure to conduct enquiries which ought to have been made rendered the assessment order erroneous and prejudicial under Explanation 2 to section 263: the tribunal held the AO should have examined prior-year treatment and available facts when assessing year end provisions, and its omission vitiated the assessment. Similarly, absence of year specific enquiry into dealership agreements, incentive schemes and nature of payments (commission) defeated any valid application of section 194H and consequent disallowance under section 40(a)(ia). No verification was carried out for capitalised jigs, fixtures, dies and moulds; these verification failures collectively justified revision under section 263 and dismissal of the appeal.

Topics

Acts Income Tax