Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
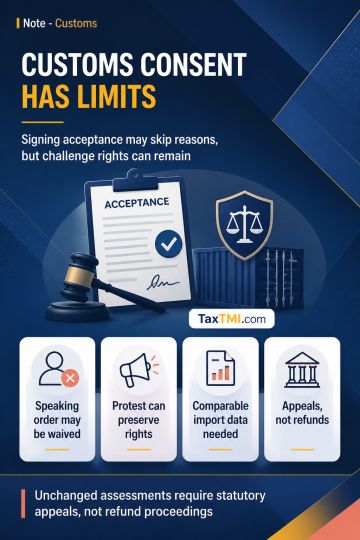
Customs transaction value rejection requires communicated reasonable doubt, while written reassessment acceptance preserves challenges to enhanced val...
Challenge-mechanism compliance clarifications permitted, while unilateral revised resolution plans may be refused under creditors' commercial discreti...
Respondent passed on the benefit of additional input tax credit to home-buyers, satisfying the anti-profiteering obligation by providing a commensurate reduction in price; the investigative report acknowledged this pass-through except for a residual payment owed to seven buyers, which the respondent agreed to remit. The tribunal accepted the investigative findings and concluded that the respondent complied with the statutory obligation to transfer GST-related ITC benefits to customers, resulting in disposal of the proceedings.
Respondent passed on the benefit of additional input tax credit to home-buyers, satisfying the anti-profiteering obligation by providing a commensurate reduction in price; the investigative report acknowledged this pass-through except for a residual payment owed to seven buyers, which the respondent agreed to remit. The tribunal accepted the investigative findings and concluded that the respondent complied with the statutory obligation to transfer GST-related ITC benefits to customers, resulting in disposal of the proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915