Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
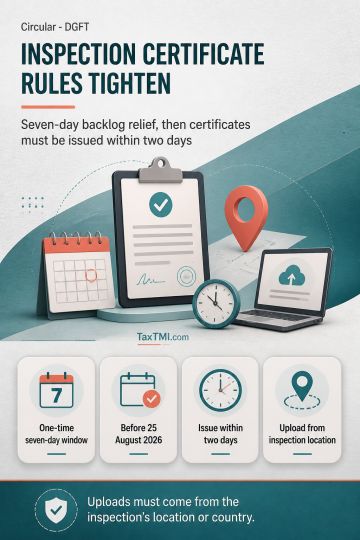
    Pre-Shipment Inspection Certificates must be issued promptly, with limited transitional relief for system-blocked backlog certificates.
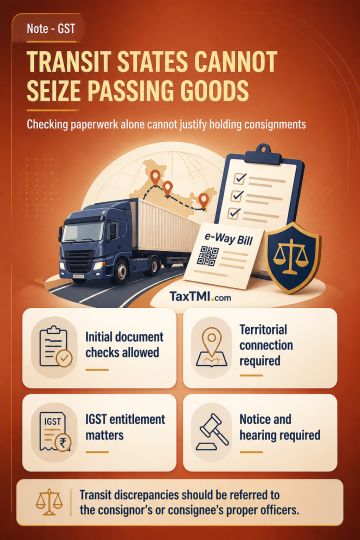
    Territorial GST jurisdiction limits detention and confiscation of inter-State consignments passing through a non-entitled transit State.
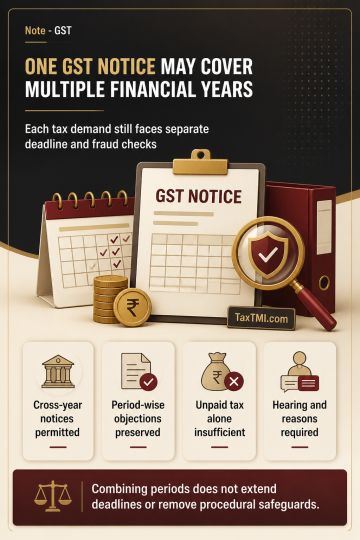
    Consolidated GST show cause notices may span financial years, but each demand component requires independent limitation and fraud scrutiny.
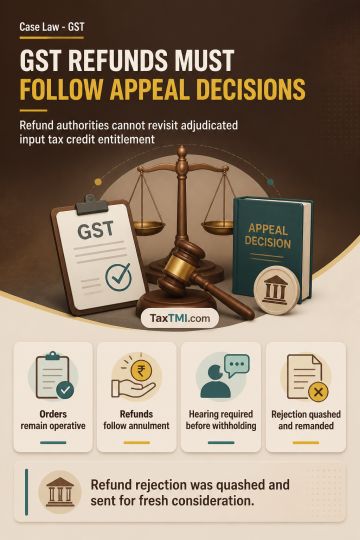
    Binding GST appellate orders require consequential refunds unless statutory withholding safeguards, including hearing, are satisfied.
    Parallel GST proceedings for one tax period were quashed while earlier exemption proceedings continue for fresh consideration.
    Rule 88C mismatch proceedings require examination before a Section 73 adjudication can be lawfully sustained.
    GST refund limitation permits writ-based delay condonation where double reversal of transitional credit requires statutory reconsideration.
    Differential GST on government works contracts must be reimbursed by the service recipient, subject to verification of records and calculations.
    Advance ruling jurisdiction under GST requires the applicant's own supply, barring questions on another person's obligations.
    Going-concern business transfers qualify as services, but exemption requires proof; otherwise transferred stock and assets are taxable goods.
    Battery-free electric vehicles retain preferential GST classification, while input-tax-credit refund claims lie outside advance-ruling jurisdiction.
    Self-invoice value for imported related-party services is deemed open market value where full input tax credit is available.
    Water-supply exemption excludes infrastructure construction and repair works, leaving pipeline works contracts taxable under GST.
    Finality of Settlement Orders Bars Reassessment of Housing-Project Deductions Already Covered by the Settlement Process
    Section 91 CrPC requires necessary search records; witness recall fails without evidence essential to a just decision.
    TDS refund entitlement under appellate give-effect orders cannot be deferred by post-assessment technical requirements alone.
    Subsequently noticed escaped income permits enlargement of pending reassessment using search material without separate pre-notice compliance.
    Income accrual for non-residents requires a real Indian nexus, defeating reassessment where rights and activity are overseas.
    Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
    MFN treaty benefits require specific domestic notification, leaving tax refund interest taxable at the Netherlands treaty interest rate.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Imported network interface cards/communication modules were...

Imported network interface cards and communication modules: CTI 8517 70 90 parts vs 8517 62 90 machines; demand time-barred

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Customs January 7, 2026 Case Laws AT
Imported network interface cards/communication modules were classifiable as "parts" under CTI 8517 70 90, not as machines under CTI 8517 62 90, because an article is not a "part" only if it can perform an independent individual function on a standalone basis; here the goods could not communicate or achieve the intended transmission function unless slotted/assembled and configured with other components, akin to parts that are functionally inseparable from the host apparatus, so the reclassification demand failed. Invocation of the extended limitation period was unsustainable because mere self-assessment and an alleged revenue-motivated classification did not establish willful misstatement or suppression on the facts, so the demand was time-barred; the impugned order was set aside and the appeal allowed. - CESTAT

Topics

Acts Income Tax