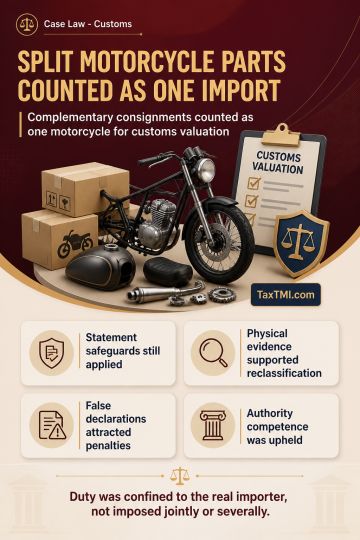
Split consignment classification treated complementary motorcycle parts as one imported motorcycle, sustaining valuation, confiscation and importer li...
Timely pronouncement of reserved judgments requires defined timelines, transparency measures, and remedial pathways to protect liberty and effective j...
Settlement-price depression requires proof of manipulation, not merely short exposure, late selling, or below-market orders, preserving disclosure pen...
The CESTAT allowed the appeal and set aside the penalty imposed under s.114(iii) of the Customs Act against the CHA. The Tribunal held that the adjudicatory record did not establish culpable conduct by the Appellant: exports were examined and passed by Customs officers, the Appellant obtained the exporter's signature on the shipping bills which constituted sufficient authorization in the absence of any prescribed proforma, and the prosecution failed to prove non-verification or fraudulent overvaluation attributable to the CHA. In consequence, statutory penalty under s.114 was unwarranted and the impugned order imposing penalty is quashed, with the appeal accordingly allowed.
The CESTAT allowed the appeal and set aside the penalty imposed under s.114(iii) of the Customs Act against the CHA. The Tribunal held that the adjudicatory record did not establish culpable conduct by the Appellant: exports were examined and passed by Customs officers, the Appellant obtained the exporter's signature on the shipping bills which constituted sufficient authorization in the absence of any prescribed proforma, and the prosecution failed to prove non-verification or fraudulent overvaluation attributable to the CHA. In consequence, statutory penalty under s.114 was unwarranted and the impugned order imposing penalty is quashed, with the appeal accordingly allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4925