Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
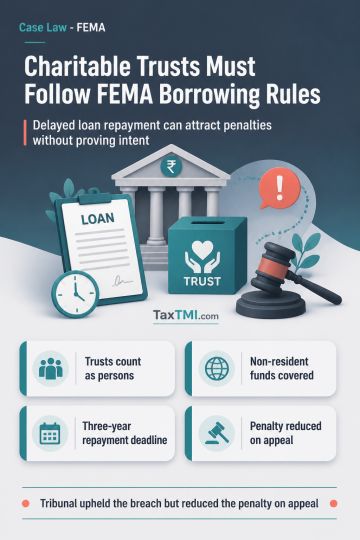
FEMA borrowing restrictions bind charitable trusts, and civil penalties apply without proving intent for delayed repayment of non-resident rupee loans...
The HC allowed the petition and set aside the impugned orders of 09.08.2024 and 30.08.2024 imposing penalty under s.129(3) of the U.P. Goods and Services Act, 2017. Although the e-way bill had expired and was not renewed, the vehicle carried the goods and invoices at inspection, and the assessing authority failed to demonstrate any material indicating an intention by the petitioner to evade tax. In the absence of requisite satisfaction as to tax-evasion intent, the technical non-compliance alone could not sustain penalty under s.129(3); accordingly the penalty orders were quashed and the petition was allowed.
The HC allowed the petition and set aside the impugned orders of 09.08.2024 and 30.08.2024 imposing penalty under s.129(3) of the U.P. Goods and Services Act, 2017. Although the e-way bill had expired and was not renewed, the vehicle carried the goods and invoices at inspection, and the assessing authority failed to demonstrate any material indicating an intention by the petitioner to evade tax. In the absence of requisite satisfaction as to tax-evasion intent, the technical non-compliance alone could not sustain penalty under s.129(3); accordingly the penalty orders were quashed and the petition was allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916