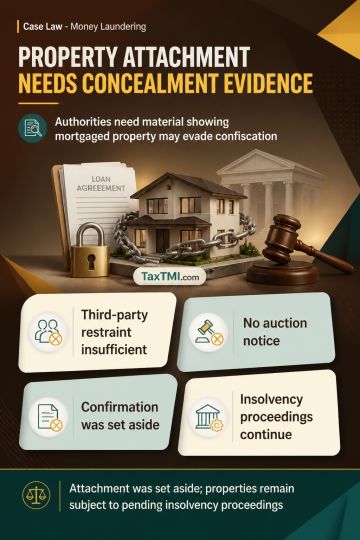
Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
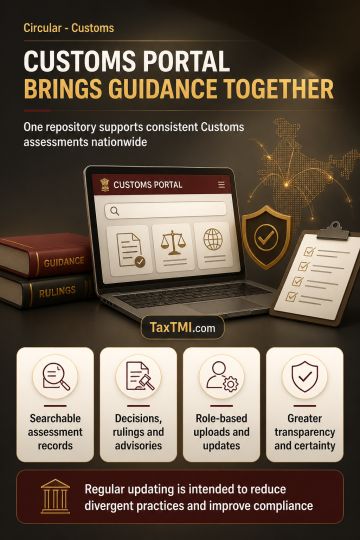
Customs assessment information portal centralises rulings and guidance to promote consistent classification, valuation, transparency and informed comp...
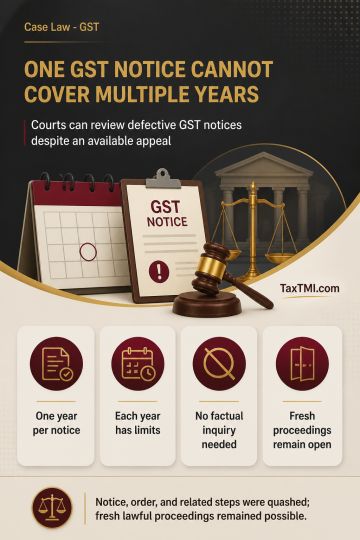
Composite show-cause notices spanning multiple financial years are jurisdictionally invalid, allowing writ review despite an alternative appellate rem...
ITAT allowed the appeal, holding that s.115BAB (concessional tax on income of new manufacturing domestic companies) and related adjustment provisions are inapplicable where the assessee has not commenced business and has no taxable income. The Tribunal found no profit even after adjustments, and therefore there was no basis to grant or deny a concessional rate, nor to invoke rules concerning shifting of profit or specified domestic transactions for the year under review. Consequently, no adjustment under the concessional-tax provisions was warranted and the ground raised by the assessee was allowed.
ITAT allowed the appeal, holding that s.115BAB (concessional tax on income of new manufacturing domestic companies) and related adjustment provisions are inapplicable where the assessee has not commenced business and has no taxable income. The Tribunal found no profit even after adjustments, and therefore there was no basis to grant or deny a concessional rate, nor to invoke rules concerning shifting of profit or specified domestic transactions for the year under review. Consequently, no adjustment under the concessional-tax provisions was warranted and the ground raised by the assessee was allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916