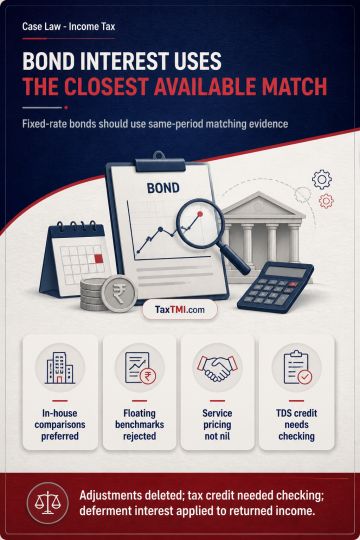
Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment...
Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments...
Bogus-purchase additions are limited to embedded profit where corresponding sales are accepted, while accommodation-entry information can support reas...
ITAT allowed the appeal, holding that s.115BAB (concessional tax on income of new manufacturing domestic companies) and related adjustment provisions are inapplicable where the assessee has not commenced business and has no taxable income. The Tribunal found no profit even after adjustments, and therefore there was no basis to grant or deny a concessional rate, nor to invoke rules concerning shifting of profit or specified domestic transactions for the year under review. Consequently, no adjustment under the concessional-tax provisions was warranted and the ground raised by the assessee was allowed.
ITAT allowed the appeal, holding that s.115BAB (concessional tax on income of new manufacturing domestic companies) and related adjustment provisions are inapplicable where the assessee has not commenced business and has no taxable income. The Tribunal found no profit even after adjustments, and therefore there was no basis to grant or deny a concessional rate, nor to invoke rules concerning shifting of profit or specified domestic transactions for the year under review. Consequently, no adjustment under the concessional-tax provisions was warranted and the ground raised by the assessee was allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916