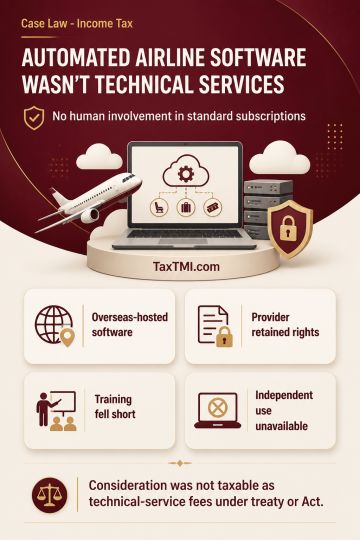
Automated airline software subscriptions without human intervention fail technical-services characterisation and do not make available underlying tech...
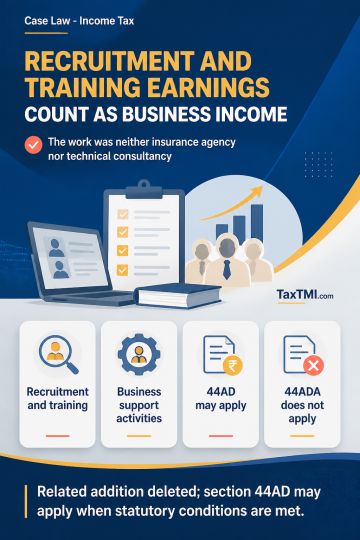
Business support recruitment and training receipts qualify for presumptive business taxation, not professional taxation under technical consultancy ru...
Treaty exemption for foreign permanent-establishment management fees prevailed, while dividend expense disallowance remained limited to an accepted al...
Centralised assessment transfers: participation after requesting centralisation can bar technical jurisdictional challenges, while assessment disputes...
Binding precedent remains operative despite pending challenge, supporting deletion of interest disallowance when debt is converted into preference sha...
ITAT dismissed the Revenue's appeal. The Tribunal affirmed that...
Depreciation on goodwill upheld; captive-generation deduction under section 80IA(4) allowed using Electricity Board supply rate; steam treated as power
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
ITAT dismissed the Revenue's appeal. The Tribunal affirmed that the allowance of depreciation on goodwill, previously settled in favour of the assessee and approved by the High Court for earlier assessment years (including AY 2007-08), stands confirmed. Further, in determining the arm's length price for purposes of deduction under section 80IA, the Tribunal held that profits and gains from an infrastructure undertaking are deductible where power is generated for captive consumption; such deduction is to be computed by reference to the rate at which the Electricity Board supplies power to its consumers. Steam produced by the assessee was characterised as "power" for the purposes of section 80IA(4), entitling the assessee to the benefit.
ITAT dismissed the Revenue's appeal. The Tribunal affirmed that the allowance of depreciation on goodwill, previously settled in favour of the assessee and approved by the High Court for earlier assessment years (including AY 2007-08), stands confirmed. Further, in determining the arm's length price for purposes of deduction under section 80IA, the Tribunal held that profits and gains from an infrastructure undertaking are deductible where power is generated for captive consumption; such deduction is to be computed by reference to the rate at which the Electricity Board supplies power to its consumers. Steam produced by the assessee was characterised as "power" for the purposes of section 80IA(4), entitling the assessee to the benefit.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4931