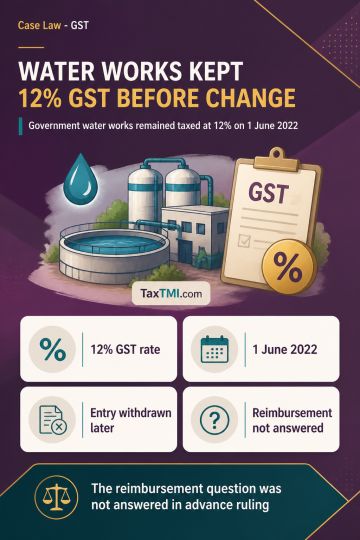
Government water works contract GST concession applied before its withdrawal, while contractual tax reimbursement claims lay outside advance-ruling sc...
Stamp valuation increases after registration-fee payment led to deletion of property-purchase addition within tolerance and without valuation referral...
Capital Asset Conversion Requires Proven Business Stock Treatment; Paper Consideration in Spousal Flat Transfers Does Not Create Taxable Business Inco...
Page of 4899
Press 'Enter' after typing page number.
701 to 720 of 97978 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
HC set aside and quashed the Appellate Authority's order dated 24.01.2023 rejecting Petitioner's refund claim for unutilized input tax credit under Section 54(3) of CGST Act and WBGST Act. The Appellate Authority improperly rejected additional documents including shipping bills without providing cogent reasons regarding their relevancy or admissibility. HC held that Rule 112(4) of CGST Rules empowers the Appellate Authority to admit additional evidence for effective adjudication. The Authority failed to exercise discretion judiciously by refusing to consider crucial evidentiary records submitted during appellate proceedings. Respondents failed to demonstrate that submitted documents were irrelevant or inadmissible for just adjudication. Petition disposed off favorably.
HC set aside and quashed the Appellate Authority's order dated 24.01.2023 rejecting Petitioner's refund claim for unutilized input tax credit under Section 54(3) of CGST Act and WBGST Act. The Appellate Authority improperly rejected additional documents including shipping bills without providing cogent reasons regarding their relevancy or admissibility. HC held that Rule 112(4) of CGST Rules empowers the Appellate Authority to admit additional evidence for effective adjudication. The Authority failed to exercise discretion judiciously by refusing to consider crucial evidentiary records submitted during appellate proceedings. Respondents failed to demonstrate that submitted documents were irrelevant or inadmissible for just adjudication. Petition disposed off favorably.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4899